By Industry Analysis Desk
Enriched and Expanded from Insights by Skip Newberry (Technology Association of Oregon) and Robert W. Cross (Outfit)
Executive Summary: The Modern Grid at a Crossroads
The modern American electrical grid is facing a structural collision of historic proportions. On one side, the explosive proliferation of artificial intelligence, cloud computing, and massive enterprise data centers is driving electricity demand to unprecedented heights. On the other side, legacy utility business models, engineered more than a century ago for predictable, slow-moving centralized generation, are struggling to keep pace.
While constructing a modern data center typically takes between 18 to 24 months, securing a stable grid interconnection now demands nearly five years on average, according to data from the Lawrence Berkeley National Laboratory. This widening temporal chasm exposes a fundamental flaw: the traditional framework governing how utilities build, finance, and operate infrastructure is fundamentally misaligned with the speed of modern technology.
As grid operators implement emergency curtailment protocols, tech giants invest heavily in decentralized "virtual power plants," and policymakers grapple with the economics of the energy transition, a new consensus is emerging. Resolving the grid crisis will require more than just building more power plants; it demands a wholesale rethinking of utility financial incentives, regulatory frameworks, and consumer participation.
Chronology of a Crisis: Key Milestones in the Grid-Data Center Bottleneck
To understand how the American energy landscape reached this critical juncture, it is helpful to trace the convergence of regulatory shifts, technological breakthroughs, and market interventions that have unfolded over recent years:
- September 2020: The Federal Energy Regulatory Commission (FERC) issues Order No. 2222, a landmark ruling that removes barriers to the participation of distributed energy resources (DERs) in wholesale capacity markets. For the first time, aggregated networks of small batteries, EV chargers, and rooftop solar arrays are granted equal footing with traditional power plants.
- 2025: Regulatory barriers begin to fall at the state level. Utah legalizes "plug-in balcony solar," sparking a wave of legislative and consumer adoption that quickly spreads to nine additional states, signaling a grassroots appetite for localized energy independence.
- June 2026: Tech giant Google signs a pioneering 100-megawatt virtual power plant (VPP) deal with distributed energy provider Voltus. The agreement aggregates thousands of flexible behind-the-counter devices and smart thermostats, demonstrating the commercial viability of software-driven capacity.
- July 2026: PJM Interconnection—the largest regional transmission organization in the United States, managing the grid across 13 states and the District of Columbia—proposes controversial new capacity auction rules. The framework allows the grid operator to temporarily curtail power to data centers during acute electricity shortages rather than mandate the immediate construction of costly new generation capacity for every projected load spike.
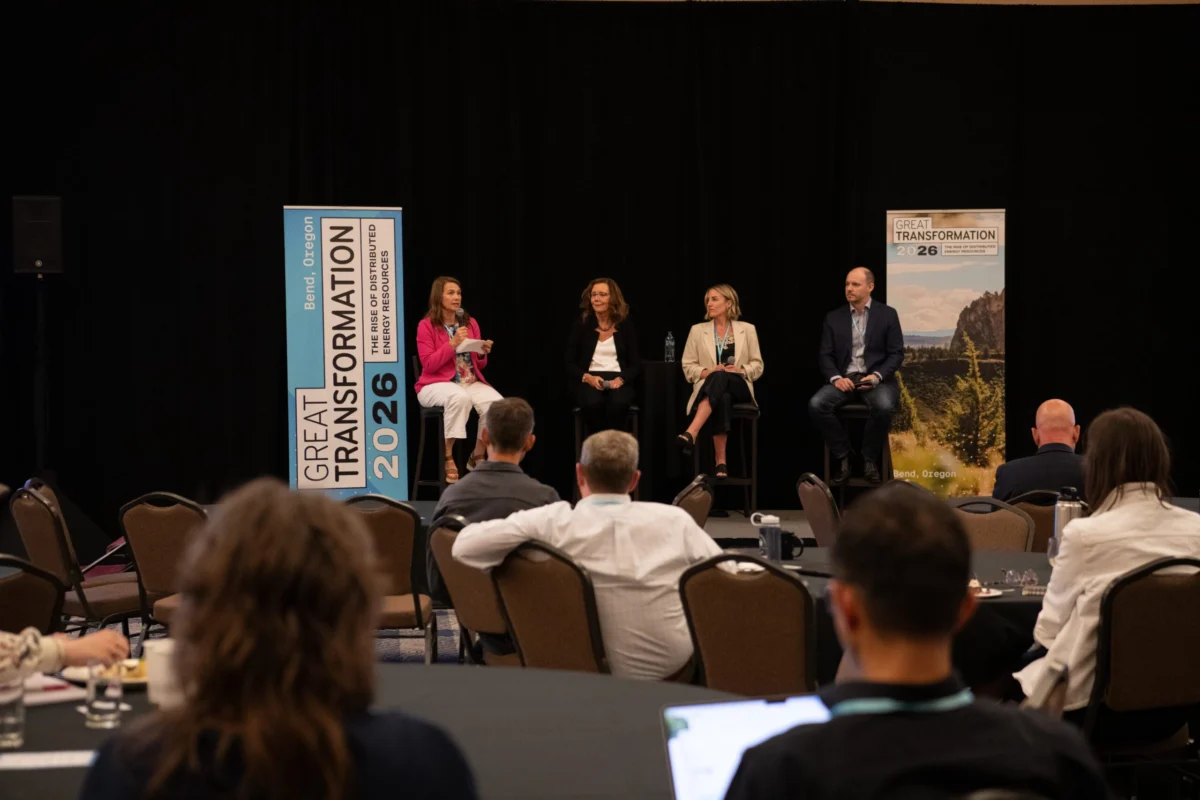
- October 2026: Industry leaders, utility executives from firms like Portland General Electric and Puget Sound Energy, and tech stakeholders gather in Bend, Oregon, for the Great Transformation summit. Discussions focus squarely on balancing rapid data center load growth with consumer affordability and regional grid resilience.
The Infrastructure Gap: Speed Versus Statutory Timelines
The friction between tech sector expansion and utility execution boils down to a profound mismatch in timelines. Digital infrastructure scales at the speed of software and venture capital, while energy infrastructure moves at the speed of civil engineering, environmental review, and public utility commission (PUC) approvals.

According to Lawrence Berkeley National Laboratory’s grid interconnection queue data, securing a spot on the power grid now takes nearly five years—more than double the wait time recorded in 2008. Meanwhile, hyperscale data centers can go from blueprint to operational status in less than two years.
This delay creates severe regional bottlenecks. In fast-growing technology hubs across the Pacific Northwest, the Mountain West, and the Mid-Atlantic, power demand is outstripping available transmission capacity. Regional transmission organizations (RTOs) are increasingly forced to choose between two unappealing options: greenlighting multi-billion-dollar transmission line projects that take decades to permit and construct, or forcing rate-paying consumers to foot the bill for peak-demand infrastructure that may sit underutilized for most of the year.
The PJM Interconnection’s July 2026 proposal to allow temporary power curtailments for data centers during emergencies highlights the desperation of grid operators. Rather than building massive new peaking plants solely to satisfy speculative AI workloads, grid operators are looking toward demand-side flexibility as a primary shock absorber.
Supporting Data & Economic Realities: The Rate Base Dilemma
While utilities are frequently cast as reluctant participants in the clean energy transition, the underlying barrier is not corporate stubbornness; it is economic design. Investor-owned utilities (IOUs) operate under a business model established decades ago, wherein profits are inextricably linked to physical capital investments.
1. The Rate Base Incentive Structure
Investor-owned utilities earn the vast majority of their returns through their rate base—the aggregate financial value of physical assets (such as power plants, substations, and transmission lines) that state regulators authorize them to own and operate.
- Regulators typically guarantee an authorized rate of return, hovering around 10% for electric utilities.
- Every dollar a utility spends on constructing large, centralized infrastructure permanently expands this rate base, securing guaranteed profits for decades.
- Conversely, operating expenditures—such as purchasing power from a third-party virtual power plant or paying a local business for demand-response services—add nothing to the rate base. They are treated as pass-through costs that generate zero long-term shareholder return.
2. The Economics of Distributed Energy Resources (DERs)
Distributed energy resources—including behind-the-meter battery storage systems, commercial rooftop solar, microgrids, and flexible smart thermostats—are located at the point of consumption rather than miles away on centralized grids.

In wildfire-prone regions like the Pacific Northwest and California, these assets serve a dual purpose: they function as economic units during normal operations and as vital life-support systems when utilities implement preemptive Public Safety Power Shutoffs (PSPS) to mitigate wildfire risks.
However, because purchasing third-party DER capacity fails to build utility rate bases, historical market structures gave utilities little financial incentive to procure these resources. A battery sitting idle behind a commercial meter earns no return for the utility, even if its availability prevents a localized blackout.
Official Responses and Strategic Shifts
Industry leaders and regulatory bodies are actively exploring structural reforms to overcome these financial disincentives. At the Great Transformation conference in Bend, Oregon, executives from utilities such as Portland General Electric (PGE) and Puget Sound Energy (PSE) debated the future of load management alongside representatives from Amazon Web Services (AWS) and the Technology Association of Oregon.
The Rise of Virtual Power Plants (VPPs)
The commercialization of Virtual Power Plants represents a major turning point in how grid capacity is procured. By aggregating thousands of disparate DERs via cloud software, companies like Google and Voltus can sell synchronized flexibility directly into wholesale energy markets.
- Value Realization: FERC Order No. 2222 laid the groundwork, but recent deals prove that VPPs are moving from theoretical pilot programs to core grid assets.
- Revenue Alignment: Under VPP frameworks, a battery or smart thermostat is no longer an idle backup device. It earns revenue for every hour it remains available to absorb excess renewable generation or discharge power during peak demand.
Consumer-Led Resilience
As institutional reforms move slowly through legislative and regulatory channels, consumers are increasingly taking matters into their own hands. Distrust in traditional centralized institutions, combined with the rising frequency of weather-related grid outages, has fueled grassroots demand for energy autonomy.
The legalization of plug-in balcony solar—pioneered by Utah in 2025 and rapidly adopted by at least nine other states—demonstrates that everyday consumers are willing to invest their own capital into micro-generation. By decentralizing power production, these technologies reduce overall strain on transmission lines without requiring massive capital outlays from investor-owned utilities.

Broader Implications for the Future of American Power
The intersection of data center expansion and grid modernization carries profound economic, geopolitical, and environmental implications.
- Economic Competitiveness vs. Ratepayer Protection: The United States cannot afford to cede its leadership in artificial intelligence and cloud computing due to power constraints. Yet, shifting the immense infrastructure costs of data center growth onto everyday residential ratepayers is politically and socially untenable. Policy frameworks must be engineered so that hyperscalers and large tech enterprises directly fund the clean, dedicated generation and storage capacity they require.
- Regulatory Modernization: State public utility commissions (PUCs) must transition from traditional cost-of-service regulation to performance-based ratemaking. By decoupling utility profits strictly from physical capital investments and rewarding them for integrating third-party DERs, efficiency, and grid flexibility, regulators can align corporate incentives with modern grid realities.
- The Shift Toward "Edge" Resilience: The paradigm of energy delivery is shifting inexorably from a top-down model (centralized power plants pushing energy over long-distance transmission lines) to a bi-directional, decentralized network. The most reliable, cost-effective kilowatt-hour is increasingly the one that never has to travel across a constrained transmission line.
Conclusion
The conversations held among technologists, utility executives, and policy experts in Bend, Oregon, point to a singular, overarching truth: distributed energy and demand-side management are no longer marginal nice-to-haves. They are absolute operational necessities for an economy driven by data and electrification.
Successfully navigating the energy transition will not require turning every consumer into a certified grid engineer. Rather, it demands forward-thinking business leaders and regulators willing to reform outmoded utility compensation models—and empowered customers ready to share responsibility for regional power reliability. As data center demand continues its relentless ascent, those who adapt to this decentralized reality will secure both economic prosperity and long-term grid resilience.