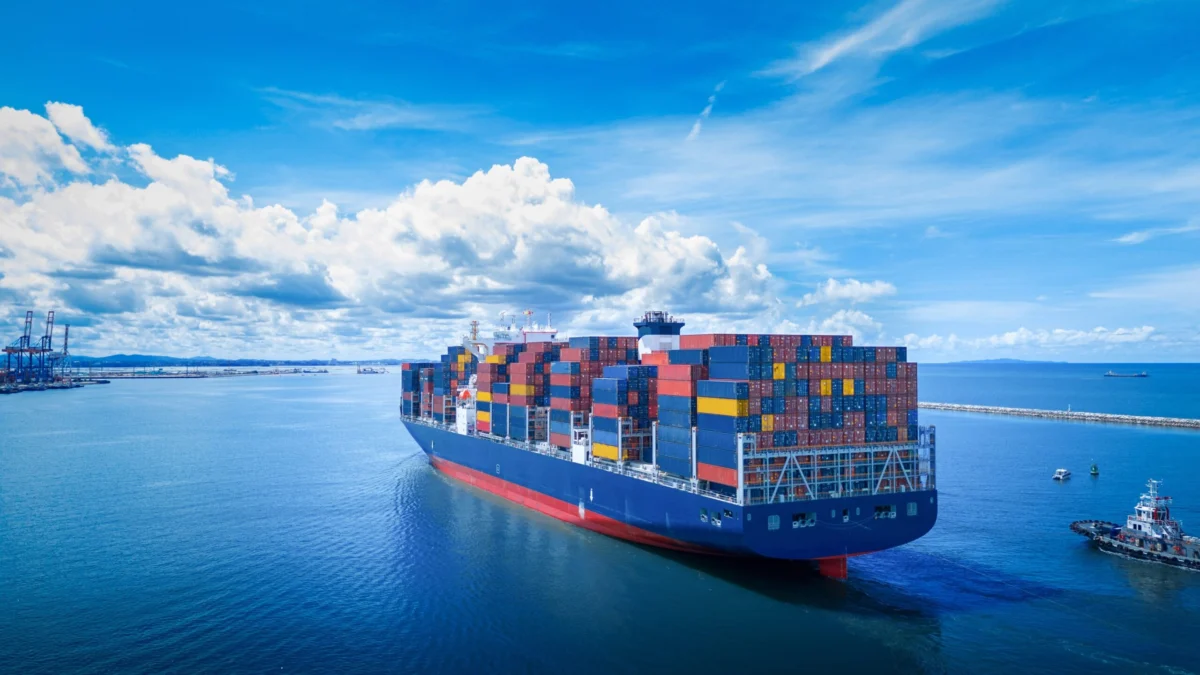

The global supply chain is once again defying expectations. According to the latest data released by the Descartes Systems Group, U.S. container imports for September 2026 reached an unprecedented milestone: 2,546,261 twenty-foot equivalent units (TEUs). This figure represents the highest September volume on record, underscoring a remarkable resilience in the American maritime logistics sector despite a landscape defined by geopolitical instability, fluctuating tariff policies, and mounting operational pressures at key port gateways.
As the industry enters the final quarter of the year, the data provided by Descartes serves as a critical barometer for logistics professionals, retailers, and policymakers alike. While the broader economic environment remains volatile, the sheer volume of goods flowing into U.S. ports suggests that consumer demand and inventory restocking efforts are holding steady, even as the infrastructure supporting these imports faces renewed strain.
The Main Facts: A Record-Breaking September
The headline figure of 2.54 million TEUs is more than just a statistical outlier; it is a testament to the robust nature of current U.S. trade. While there was a marginal month-over-month decrease of 2.2% from August—a typical seasonal cooling—the year-over-year growth tells a more compelling story. September 2026 volumes were 10.3% higher than those recorded in September 2025 (2,307,933 TEUs) and a staggering 24.8% above pre-pandemic levels seen in September 2019 (2,040,813 TEUs).
Perhaps most significantly, the cumulative import volume for the first nine months of 2026 has officially tipped into positive territory. For the first time this calendar year, total year-to-date imports have surpassed 2025 levels by 0.8%. This transition from a lagging growth trend to a positive one indicates that the shipping sector has successfully navigated the turbulence of the previous winter and spring, finding its footing as the peak shipping season progressed.
Chronology and Trend Analysis
To understand the current state of maritime trade, one must look at the progression of the year. The early months of 2026 were characterized by a cautious approach from importers, largely due to lingering inventory gluts from the previous year and economic uncertainty regarding interest rates and inflation.
- Q1-Q2 2026: The year began with relatively flat growth. Importers were hesitant to commit to large-scale inventory expansion as they monitored consumer spending patterns.
- Summer 2026: As mid-year approached, a shift became apparent. Retailers, wary of potential supply chain bottlenecks later in the year, began pulling forward orders. This trend, often referred to as "front-loading," became a defining characteristic of the summer months.
- September 2026: The record-breaking volume in September represents the culmination of this front-loading strategy. The surge indicates that companies were not only preparing for the holiday shopping season but were also perhaps preempting potential disruptions in international shipping lanes or changes in trade regulations.
This chronological progression demonstrates a shift from reactive logistics to proactive, risk-mitigated supply chain management. The data suggests that shippers are increasingly comfortable with higher inventory levels, prioritizing availability over the cost-savings associated with "just-in-time" models.
Supporting Data: The China Factor and Global Origins
A significant driver of September’s record-breaking numbers was the rebound in imports from China. China-origin imports reached 924,454 TEUs, marking a 4.5% increase month-over-month and a dramatic 21.2% rise compared to September 2025.
China’s share of total U.S. container imports expanded from 34.0% in August to 36.3% in September. This concentration remains highly focused on three key product categories:
- Plastics (HS-39): 135,097 TEUs (14.6% of China-origin volume).
- Furniture and Bedding (HS-94): 123,574 TEUs (13.4% of China-origin volume).
- Toys and Sporting Goods (HS-95): 92,842 TEUs (approximately 10% of China-origin volume).
While China saw growth, other top-tier trading partners experienced a more mixed performance. While India and Taiwan reported modest gains, seven of the top 10 countries of origin saw a decline in import volumes. This suggests a consolidation of trade flows back toward larger, more established manufacturing hubs as shippers seek to streamline their logistics in an environment of high freight costs and limited capacity.
Port Infrastructure and Transit Delays
A sobering component of the September data is the increase in port transit delays. Eight of the top 10 U.S. ports reported longer wait times compared to the previous month. This creates a paradox: while the U.S. is successfully importing more goods than ever, the infrastructure is reaching its threshold for efficiency.
The shift in market share from East and Gulf Coast gateways to West Coast ports is also notable. As shippers look to avoid potential labor disputes or congestion in the East, the migration of volume toward Pacific gateways has put additional pressure on West Coast rail and truck drayage capacity. These bottlenecks, while currently manageable, serve as a warning for the coming months, particularly if volumes remain at these elevated levels through the end of the year.

Official Perspectives: The Expert View
Jackson Wood, VP of Product Management for Trade Regulations at Descartes, emphasized that the record-breaking September figures are a double-edged sword. "Record September import volumes show that U.S. maritime trade remains remarkably strong despite persistent trade and geopolitical pressures," Wood noted.
However, he cautioned against complacency. "Strong demand is coinciding with rising port delays, evolving tariff requirements, and continued risk across critical shipping corridors," Wood explained. His assessment highlights the reality that high volumes do not necessarily equate to high margins or operational ease. For the modern supply chain leader, the challenge has shifted from "getting goods" to "managing the complexity of the arrival."
Wood advocates for a strategy of "total visibility." In his view, the companies that will thrive in the current climate are those that have invested in the technological infrastructure to monitor costs, capacity, and routing in real-time. The ability to pivot sourcing origins or port gateways at short notice is no longer a luxury; it is a fundamental requirement for business continuity.
Strategic Implications for the Supply Chain
The implications of the September 2026 data are far-reaching for logistics professionals.
1. The Necessity of Flexibility
The volatility of the current environment—where one month can see a 24.8% increase over historical norms—proves that static supply chain planning is obsolete. Companies must maintain a "multi-modal" and "multi-gateway" approach to ensure they are not tethered to a single point of failure.
2. The Cost of Congestion
With eight of the top 10 ports experiencing delays, the cost of "hidden" logistics—such as demurrage, detention, and extended warehouse storage—is likely to rise. Shippers should factor these costs into their end-of-year financial forecasting, as the expense of moving a container is no longer just the ocean freight rate, but the total time-to-market.
3. Geopolitical Preparedness
The reliance on China for 36.3% of total imports, while indicative of the deep integration of global manufacturing, also poses a systemic risk. As trade regulations evolve and potential tariff structures are debated, importers should conduct "stress tests" on their supply chains to see how a sudden shift in trade policy might impact their ability to source essential goods like plastics and furniture.
4. Technological Integration
Descartes’ focus on providing data-driven insights underscores the industry’s shift toward digitization. Companies that rely on legacy systems to track their goods will find themselves at a disadvantage compared to competitors utilizing AI-driven forecasting and real-time monitoring of maritime corridors.
Conclusion: Looking Ahead
The September 2026 data serves as both a celebration of resilience and a call to action. The U.S. maritime sector has proven it can handle record volumes, but it is doing so while operating at the very edge of its capacity. As the industry looks toward the remainder of the year, the focus must remain on agility, visibility, and proactive risk management.
For logistics professionals, the roadmap is clear: the volatility that defined 2026 is likely to persist. Whether it is navigating the ripple effects of shifting manufacturing hubs or mitigating the impact of port congestion, success will belong to those who can effectively synthesize data into actionable strategy. By leveraging resources such as the Descartes Global Shipping Resource Center, firms can ensure they are not merely reacting to the record-breaking volumes of today, but building the resilient supply chains of tomorrow.