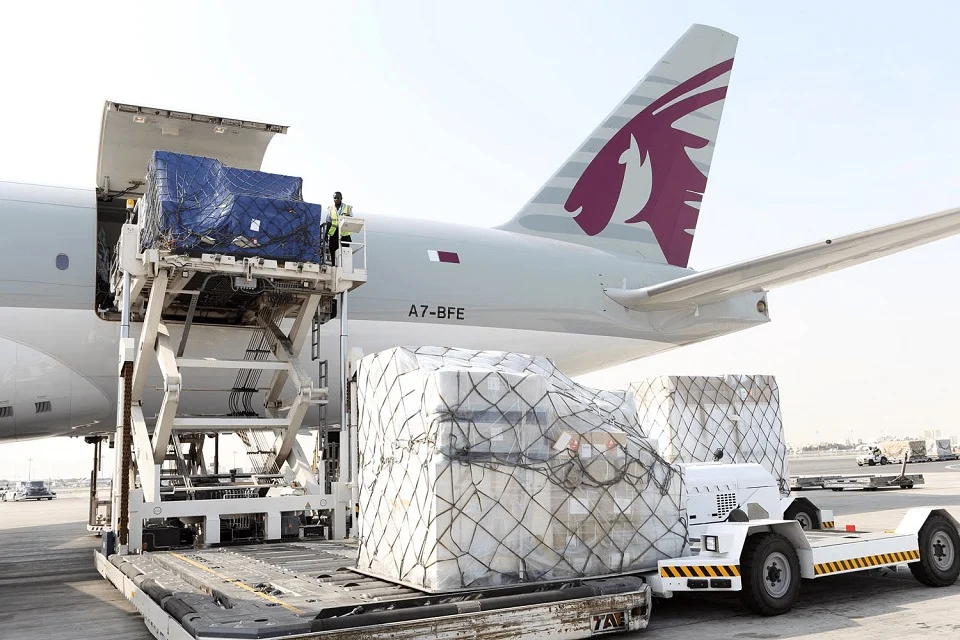

LONDON — Global airfreight markets have entered uncharted territory for the pre-holiday season, as new pricing data reveals a sharp, broad-based surge in cargo transport costs. According to the latest figures from TAC Index—the premier price reporting agency for airfreight markets and the calculating agent for the Baltic Air Freight Indices—worldwide shipping rates have rebounded aggressively from a brief, holiday-induced dip, climbing well past the peak thresholds observed during the comparable periods of the last two years.
The sudden upward trajectory highlights a logistics landscape severely pressured by persistent macroeconomic headwinds, regional conflicts, and structurally higher operational expenditures for carriers. As retailers and manufacturers rush to secure cargo capacity ahead of the critical consumer shopping window—traditionally anchored by Thanksgiving in the United States and Christmas in Europe—the underlying dynamics of the air cargo sector indicate that high pricing is here to stay.
Main Facts
The most recent data released by TAC Index underscores a market experiencing intense upward pricing pressure. For the seven-day period leading up to October 19, the global Baltic Air Freight Index recorded a remarkable 4.7% single-week jump. This movement pushed the aggregate index to a staggering 26.4% higher than the same period in the previous year.
Crucially, these current valuations have already outpaced the apex pricing points recorded during the peak seasons of the past two years. Industry observers note that this anomaly is driven not merely by seasonal demand, but by a compounding baseline of structural market disruptions.
At the center of these disruptions are persistent geopolitical conflicts, notably the ongoing war between Russia and Ukraine and escalating tensions in the Middle East. These flashpoints have fundamentally altered global trade routes, forcing costly detours and driving up fuel consumption. According to data from the International Air Transport Association (IATA) Jet Fuel Price Monitor, jet fuel prices have skyrocketed by an astronomical 113.7% year-on-year as of mid-October.
Market analysts at TAC Index point out that this immense fuel cost inflation creates an unyielding baseline for the industry. Specifically, it establishes a "hard floor" beneath the rates that commercial and cargo airlines must charge simply to break even on operating expenditures, virtually guaranteeing that baseline pricing will remain elevated for the foreseeable future.
Chronology of Market Movements
To fully understand the current pricing spike, industry analysts have examined the sequential progression of market data over recent weeks, tracking how temporary holiday lulls gave way to aggressive upward corrections.
Early October: The Golden Week Lull
Earlier in the month, the airfreight sector experienced a brief, expected moderation in pricing. Figures released for the week ending October 12 indicated a modest 2.1% retraction in the Baltic Air Freight Index.
Industry experts were quick to contextualize this dip, attributing it directly to China’s annual "Golden Week" celebrations. During this major holiday period, factories across mainland China routinely scale back operations or close entirely, leading to a temporary reduction in outbound cargo volumes. TAC Index noted at the time that such a contraction was entirely routine for the seasonal calendar and did not signal a structural weakening of the broader market. Instead, the agency maintained that the sector was retaining a remarkably firm posture as it braced for the heavy lifting of the fourth-quarter peak season.
Mid-October: The Post-Holiday Rebound
The resilience predicted by analysts materialized almost immediately following the resumption of factory activity in China. In the subsequent seven-day window leading to October 19, the market erased the minor Golden Week losses and surged past previous baselines.
The 4.7% weekly leap captured in the latest Baltic Air Freight Index data demonstrated that pent-up manufacturing output and urgent replenishment needs quickly overwhelmed available capacity, igniting a fresh wave of spot-rate increases that caught some forwarders off guard.
Supporting Data: Geographical Variations
While the global average tells a story of sweeping increases, a closer examination of regional trade lanes reveals a fragmented landscape characterized by stark geographical divergence.
Asia-Pacific and Transpacific Lanes
The primary catalyst for the recent global rate surge originated in Asia, led by powerful outbound momentum from China’s key manufacturing hubs. Spot rates out of Hong Kong and Shanghai registered substantial increases.
Particularly strong week-on-week gains were recorded on the busiest trunk routes from China to the United States. Lanes connecting China to Europe also experienced upward pressure, though the European inbound market has faced unique headwinds since July. Volumes into the European Union have lagged somewhat following the regulatory elimination of the old de minimis customs duty exemption for low-value small parcels—a policy change that has noticeably altered e-commerce shipping volumes into the continent.
European Hubs and Transatlantic Shifts
In contrast to the aggressive bullishness seen in Asian export markets, outbound rates from major European hubs softened somewhat during the mid-October reporting period.
- Frankfurt: The index tracking outbound routes from Frankfurt experienced a 6.6% week-on-week decline. Despite this short-term dip, Frankfurt’s rates remain exceptionally robust from a macro perspective, sitting 33.7% higher than they were at the same point last year.
- London Heathrow: Outbound rates from London’s primary gateway slipped by 2.3% week-on-week, yet they continue to dwarf historical norms, holding steady at an impressive 35.2% year-on-year increase.
Furthermore, transatlantic lanes heading west from Europe toward the United States showed downward movement. European outbound pricing also softened on routes targeting India, Japan, Australia, and South Africa. However, these losses were partially offset by continued strength on European export lanes directed toward China, Mexico, Brazil, and the United Arab Emirates.
North American and Latin American Corridors
North American outbound airfreight markets displayed a generally firm posture. Rates climbed week-on-week on lanes connecting the US to China and the broader Asian market, as well as on key routes heading into South America. This regional strength was spearheaded by ongoing upward momentum on southbound trunk routes originating from Miami—a crucial gateway for the Americas.
Conversely, mirroring the transatlantic softening seen from Europe, US outbound rates destined for European and UK markets experienced slight contractions. Meanwhile, Latin American corridors demonstrated significant vigor, highlighted by another substantial week-on-week rate spike on routes originating in Mexico and heading toward Europe, keeping Mexican export pricing firmly in positive year-on-year territory.
Official Responses and Industry Commentary
The sustained escalation of airfreight pricing has drawn intense commentary from market monitors, airline executives, and logistics providers.
Representatives from TAC Index have emphasized that the current pricing environment is fundamentally different from the pandemic-era logistics crunches, yet it shares a similar vulnerability to external shocks. By highlighting the dramatic 113.7% year-on-year increase in jet fuel prices, reporting agencies have underscored that airlines possess very little room to maneuver regarding discounting.
"The combination of geopolitical flashpoints in Eastern Europe and the Middle East has institutionalized a high-cost operating model for international aviation," noted industry analysts tracking the IATA Jet Fuel Price Monitor. "When fuel expenses double over a twelve-month period, carriers are forced to pass those costs downstream to maintain operational viability. This creates a hard floor beneath cargo rates that will prevent any meaningful market correction in the near term."
Freight forwarders have similarly reported that clients are increasingly accepting of higher rates, driven by the urgency of maintaining supply chain continuity ahead of holiday shopping deadlines. Shippers are prioritizing guaranteed uplift over cost minimization, fearing that any delay in securing cargo space could leave store shelves empty during the most critical retail period of the year.
Implications for Global Supply Chains
The implications of sustained, high-level airfreight rates ripple across the entire global economy, affecting manufacturers, retailers, and end consumers alike.
1. Margin Pressures for Retailers and E-Commerce
With baseline air cargo costs sitting significantly higher than historical averages—and well above the peaks of the past two years—retailers operating on tight profit margins face difficult choices. Companies specializing in high-value, time-sensitive goods, such as consumer electronics, fashion apparel, and perishable pharmaceuticals, must decide whether to absorb these elevated logistics expenses or pass them on to consumers through higher retail prices. The latter option risks dampening consumer demand during a period already marked by inflationary pressures.
2. Strategic Shifts in Inventory Management
The persistent volatility and high cost of airfreight are accelerating long-term structural changes in supply chain management. Shippers are increasingly looking to optimize their modal split, relying more heavily on ocean freight for non-urgent inventory while reserving air cargo strictly for high-priority replenishment. However, ongoing geopolitical disruptions in maritime corridors—such as security challenges in the Red Sea—have frequently compromised the reliability of ocean shipping, leaving airfreight as the indispensable fallback option despite its premium cost.
3. Outlook for the Peak Season and Beyond
As the air cargo industry pushes deeper into its traditional peak operating window, the overarching consensus among market data providers is one of unyielding firmness. With structural cost floors established by soaring fuel prices, constrained capacity on key Asian export corridors, and enduring geopolitical friction, a sudden collapse in freight rates appears highly unlikely.
For logistics planners and cargo operators, the message is clear: navigating the remainder of the year will require agile capacity management, close monitoring of regional rate disparities, and a strategic acceptance of a permanently elevated cost baseline in global air transport.