On October 15, the Financial Stability Board (FSB)—the international body that monitors and makes recommendations about the global financial system—issued a definitive set of 12 "Sound Practices" for the responsible adoption of artificial intelligence (AI). This landmark guidance represents a critical pivot in the global financial regulatory landscape, moving from broad, philosophical discussions about AI ethics to the concrete, operational realities of risk management.
By placing senior management accountability and robust human oversight at the core of its recommendations, the FSB has signaled that AI is no longer merely a "technology project" for the IT department. Instead, it is a core governance challenge that strikes at the heart of how banks, insurers, and asset managers operate.
The Chronology of Oversight: From Theory to Practice
The journey to this framework has been characterized by a rapid escalation in both AI capability and regulatory concern.
- November 2024: The FSB published a pivotal assessment highlighting the systemic risks associated with AI, including third-party concentration, market correlations, and potential model-related instabilities. This report laid the conceptual groundwork for the necessity of tighter institutional controls.
- Early 2025: Throughout the year, international financial regulators expressed increasing anxiety over "agentic" AI—systems capable of performing tasks and making decisions with minimal human intervention.
- Mid-2025: The FSB opened a consultation process, inviting feedback from the industry. A recurring theme in the feedback was the need for "operational feasibility"—the realization that oversight must be more than a checkbox exercise if it is to be meaningful.
- October 15, 2026: The FSB finalized the 12 practices, incorporating feedback specifically regarding highly autonomous systems and the realities of cross-border financial dependencies.
The resulting document is intentionally non-prescriptive, acknowledging that a regional lender and a global investment bank have vastly different risk profiles. Rather than imposing a binding standard, the FSB provides a flexible toolkit that encourages firms to apply governance proportionately to their specific circumstances.
Supporting Data: The Anatomy of Risk in Lending Workflows
To understand why the FSB emphasizes "human oversight," one must analyze the progression of AI authority in a typical financial workflow, such as small business lending.
Level 1: The AI Assistant (Extraction)
At the lowest level of risk, an AI reads financial statements and extracts data for a human credit officer. The risk here is primarily one of accuracy. If the AI misreads a revenue figure, a human reviewer can catch it during the validation phase.
Level 2: The Agentic Workflow (Execution)
The risk profile shifts dramatically when the AI is granted "delegated authority." If the system can not only extract data but also update customer records or approve credit limits, the potential for harm increases exponentially. An error in the first step—if unmonitored—becomes the faulty foundation for the next.
The FSB suggests a "stress test" approach for these systems: institutions should deliberately introduce errors (e.g., a missing document or a conflicting debt figure) to see if the system records the uncertainty, requests human help, or proceeds with a dangerous, unsupported assumption.
Official Responses and the Reality of Governance
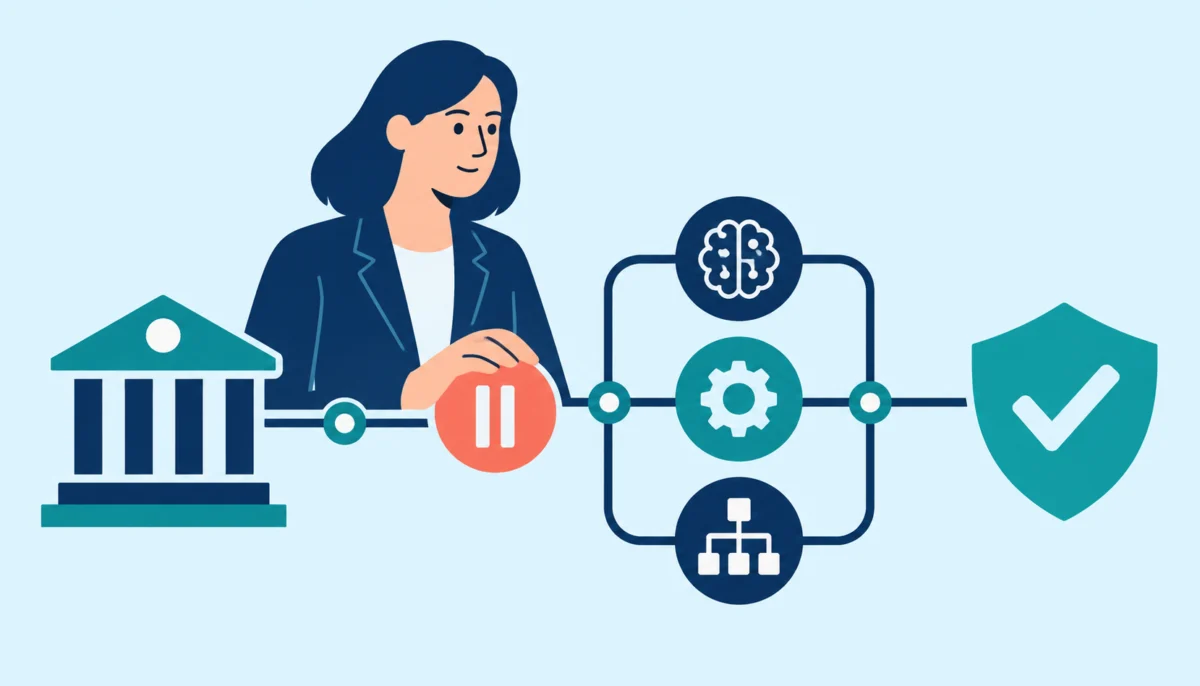
The FSB’s consultation response highlights a critical realization: counting approval buttons is not the same as exercising oversight.
The FSB warns against the "rubber-stamp" trap. If a human reviewer is tasked with clearing hundreds of complex loan files in a short window, they lack the "genuine authority" and time to provide meaningful challenge. Similarly, if a manager receives an automated alert but lacks the system permissions to hit a "kill switch" and pause the service, the oversight is purely cosmetic.
Effective oversight requires:
- Documented Authority: Clear definitions of what the AI can and cannot do.
- Operational Feasibility: A documented path for what happens when an exception occurs.
- Continuity Planning: A "restricted operating mode" that allows the business to function, perhaps at a slower pace, while the AI is offline for investigation.
The Hidden Danger: Shared Technology and Systemic Risk
One of the most profound sections of the FSB’s guidance addresses the "third-party concentration" risk. Financial institutions often outsource their AI capabilities to a small handful of cloud and model providers.
Even if two banks use different software vendors, they may be running on the same underlying large language model (LLM) or infrastructure provider. This creates a "hidden" correlation. If that common provider experiences a systemic outage or a "model hallucination" event, multiple institutions could be affected simultaneously.
The FSB’s guidance forces firms to look beyond the immediate vendor contract. Institutions must conduct "sub-service" due diligence, examining the stability of the foundation upon which their AI tools are built. As the report notes, the economic value of redundancy is zero if that redundancy fails during a market stress event.
Implications for the Future of Finance
For Credit Analysts: The Need for Evidence
Analysts must now scrutinize whether an institution’s efficiency gains are sustainable or merely a result of loosening risk standards. Key metrics to track include:
- Exception Rates: How often does the system fail, and how is it corrected?
- Independent File Reviews: Do human audits confirm that AI-driven decisions align with historical repayment assessments?
- Model Change Testing: Does the institution have a protocol to re-verify AI performance after every update or patch?
For Operational Resilience
The cost of AI is not just the software license; it is the cost of the "monitoring layer." Firms must map their critical services against their technology providers. If a bank’s AI-powered payment service goes down, what is the cost of remediation? Does the bank have the staff capacity to process those payments manually? These are no longer hypothetical IT questions; they are core balance-sheet issues.
For Investors and Earnings Expectations
Investors should be wary of firms claiming "AI-driven cost savings" without also disclosing the recurring expenses of human oversight. The true cost of AI adoption includes the wages of the teams monitoring the systems, the expense of periodic stress testing, and the potential liability of errors. A credible business case must explicitly separate the benefits of "decision preparation" from the benefits of "autonomous execution."
Conclusion: A New Era of Accountability
The FSB’s October 15 framework is a watershed moment for the financial sector. It acknowledges that while AI offers immense potential for efficiency and service delivery, it also introduces a "black box" that can obscure risk until it is too late.
By forcing firms to document their control processes, define the limits of autonomous agency, and prepare for system failures, the FSB is moving the industry toward a more mature phase of adoption. The ultimate measure of success will not be how many AI applications a bank has deployed, but rather the transparency of its "documented authority" and the resilience of its "interruption procedures."
As these practices are integrated into the operating records of the world’s largest financial institutions, investors and regulators alike will have the data necessary to judge whether AI is truly enhancing the economics of finance or merely shifting risk into new, more difficult-to-detect corners of the market. The era of "AI at any cost" is over; the era of "responsible, accountable AI" has begun.