By Bill Mitchell, Senior Business Unit Director, Renewables & Energy Infrastructure at Jabil
Edited by Sean Wolfe
Main Facts: The Evolving Landscape of Energy Storage
Lithium-ion technology—particularly lithium iron phosphate (LFP)—has cemented its position as the undisputed backbone of the global stationary energy storage market. Backed by decades of refinement, massive manufacturing gigafactories, robust supply chains, and proven bankability at scale, LFP will likely continue to dominate the sector for the next decade.
However, the energy transition is far too dynamic for a one-size-fits-all approach. As the power grid modernizes, renewable penetration deepens, and artificial intelligence (AI) data centers drive unprecedented electricity demand, specific use cases are emerging where alternative battery chemistries hold a distinct advantage. Emerging technologies—including sodium-ion, flow batteries, and iron-air systems—are beginning to carve out niches by offering lower costs, extended storage durations, superior cold-weather performance, and enhanced safety profiles.
To navigate this evolving landscape, energy storage system (ESS) manufacturers can no longer rely on rigid, single-chemistry product lines. Instead, the industry must pivot toward adaptable architectures and flexible manufacturing processes capable of seamlessly integrating diverse battery chemistries as market demands shift.
Chronology: From Early Lithium Deployment to Next-Gen Alternatives
The trajectory of grid-scale energy storage mirrors the technological maturation curves seen in other high-tech sectors:
- 15 Years Ago: Lithium-ion batteries were first deployed for grid storage applications. At the time, installations were sparse. While industry pioneers believed in the technology’s long-term viability, financial institutions and project developers hesitated to shoulder the immense risk associated with unproven grid-scale assets.
- The LFP Boom: Through continuous capital investment, technological refinement, and the scaling of global manufacturing hubs, LFP transformed from a high-risk gamble into the primary bankable technology deployed across the globe today.
- Present Day: A parallel challenge is unfolding. Promising emerging storage technologies—such as sodium-ion, flow, and iron-air batteries—face the exact hurdle lithium-ion cleared a decade ago: proving reliable performance, long-term durability, and bankability at scale.
- The 2030 Horizon and Beyond: Industry consensus indicates that lithium-ion will retain market dominance over the next ten years. Meaningful commercial adoption of alternative chemistries, particularly sodium-ion, is widely projected to accelerate rapidly only after 2030, once manufacturing capacity, field data, and supply networks mature.
Supporting Data: Evaluating Alternative Battery Technologies
Different chemistries excel at different jobs. When evaluating alternatives to lithium-ion, engineers and developers must weigh technical metrics such as energy density, cycle life, thermal performance, and safety against economic realities.
Sodium-Ion Batteries: The Closest Competitor
Sodium-ion is widely regarded as the closest functional competitor to lithium, though reaching substantial adoption and true cost parity is unlikely before the end of the decade.
- Advantages: Sodium-ion offers exceptional performance in cold-weather environments and can operate in temperatures up to 55°C without active cooling—making it an ideal backup power solution for data centers. For rapid-cycling applications, sodium batteries often feature a smaller physical footprint than lithium. Furthermore, because their manufacturing process closely mirrors that of lithium-ion (particularly at the module and system levels), established battery manufacturers can transition production lines with relative ease.
- Challenges: Certain sodium-ion variants require exceptionally strict thermal management. Under specific conditions, they can experience thermal runaway at lower temperatures, potentially releasing up to 2.5 times the volume of gas compared to equivalent lithium systems.
- Best Fit: Grid-scale and industrial applications where weight and volume constraints are less stringent.
Flow Batteries: Scaling for Long-Duration Storage
As the energy market shifts away from standard two- and four-hour storage systems toward six-, eight-, and multi-hour durations, flow batteries (including vanadium- and zinc-based systems) are gaining traction.
- Advantages: Unlike lithium-ion cells, which inherently degrade and lose capacity over time, flow batteries can remain fully charged or fully discharged for extended periods without capacity loss. Crucially, they achieve economic scaling simply through the sizing of their electrolyte tanks; a baseline 1-megawatt (MW) system can be scaled to four, eight, or 12 hours of storage merely by adjusting tank dimensions.
- Challenges: Flow systems carry a inherent risk of fluid leaks, necessitating rigorous secondary containment at both the container and pad levels, which adds to overall project costs. While a handful of companies have secured gigawatt-hour-scale agreements, flow batteries represent a tiny fraction of the broader market. They urgently require broader field validation and operational track records to satisfy financiers.
Iron-Air Batteries: Multi-Day Storage Potential
Iron-air batteries compete in the ultra-long-duration space, capable of delivering capacities stretching up to 100 hours.
- Mechanism: These multi-day storage systems capture and release energy through the controlled rusting and "unrusting" of iron, driven by electrical currents.
- Advantages: Compared to flow systems, iron-air batteries require less maintenance and benefit from lower material costs.
- Challenges: The chemical "unrusting" process can induce component degradation over time. Additionally, iron-air systems are physically large and feature slower response times than lithium or sodium cells. Whether iron-air holds a cost advantage over flow batteries depends entirely on project-specific constraints.
Official Responses and Industry Perspectives: Driving Forces and Supply Chain Shifts
The primary catalyst driving the industry away from a strict mono-technology model is total system cost relative to application demands.
While lithium-ion benefits from entrenched manufacturing ecosystems, high energy density, and vast deployment data, it cannot economically or technically satisfy every use case. Applications requiring sub-freezing performance, ultra-high cycle lives, extremely rapid charging, or multi-day storage durations necessitate alternative solutions.
Supply Chain Security and Regionalization
Supply chain dynamics are actively fueling the diversification movement. The traditional lithium-ion supply chain is capital-intensive, highly controlled, and heavily concentrated in key international regions—predominantly China—which introduces severe price volatility, logistical bottlenecks, and geopolitical risk.

In response, North American and European markets are aggressively building domestic supply networks. In the United States, initiatives span direct brine extraction and newly identified lithium reserves in Texas, Louisiana, and Utah’s Great Salt Lake.
Concurrently, the industry is racing to establish sodium-ion supply chains. Because sodium is the sixth most abundant element on Earth, it unlocks opportunities for highly localized manufacturing, significantly mitigating energy security concerns and insulating project developers from commodity price shocks.
Implications: Building Flexibility into Production and Customer Choices
Because no market analyst or engineer can definitively predict which storage technology will capture dominant market share five years from now, battery original equipment manufacturers (OEMs) must bake agility directly into their product architectures and manufacturing floors.
Architectural Flexibility for OEMs
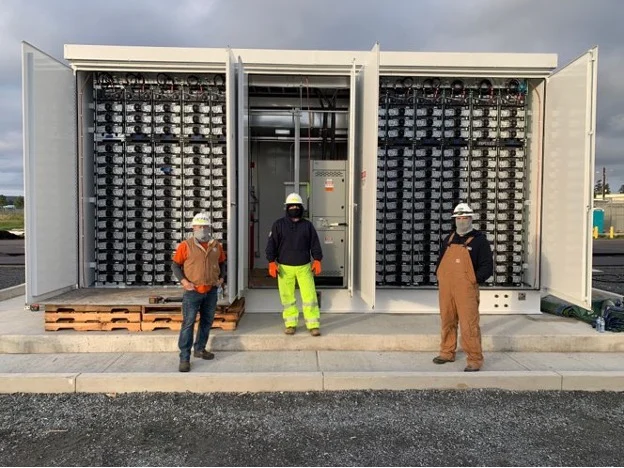
At the system level, most stationary storage technologies share fundamental design traits outside of the electrochemical cell itself: they are housed in enclosures or containers, governed by similar power conversion and balance-of-plant systems.
This structural similarity presents an opportunity for OEMs to design configurable, agnostic platforms. Instead of forcing a single, rigid system configuration across all projects, manufacturers should develop modular platforms capable of accommodating diverse cell formats and chemistries as the market matures. The ultimate competitive differentiator will be the engineering capability to integrate new chemistries without necessitating a complete system redesign or a total overhaul of the manufacturing process. Standardized mechanical, electrical, thermal, and control interfaces will be the building blocks of this flexibility.
Expanded Choices for End-Users
Ultimately, the future of energy storage is not about supplanting lithium with a single successor; it is about expanding the industry’s technological toolkit.
Grid operators, commercial developers, and enterprise customers will increasingly benefit from application-specific optimization. For instance:
- A utility-scale project requiring 12 hours of capacity for renewable shifting may favor a flow or iron-air battery.
- An artificial intelligence data center requiring ultra-fast power delivery, high reliability, and a compact footprint in warm environments may prioritize advanced lithium-ion or sodium-ion configurations.
This technological diversity fosters robust market competition, drives down costs, and empowers project owners to maximize profitability across a wider spectrum of specialized energy applications.
About the Author
Bill Mitchell is a senior business executive with a proven track record of delivering leadership and strategic vision in emerging and high-technology product markets, driving growth across companies and teams within complex international environments.
Bill leads the Energy Storage strategy for Jabil’s Renewable Energy and Infrastructure division, including the startup of their ESS manufacturing center of excellence in the U.S. Throughout his career, he has managed P&L responsibility exceeding $1 billion across multiple business units, spanning energy storage, EV charging, solar power conversion, and data center power and cooling solutions.
With over 30 years of experience in clean energy technologies, Bill has built deep expertise across all core business operations. Prior to joining Jabil, he served as Vice President of Sales and Marketing for grid and commercial energy storage products at A123 Systems. Earlier in his career, he co-founded Nuvera Fuel Cells, now a subsidiary of Hyster-Yale Material Handling, Inc.
Bill holds a Bachelor of Science and a Master of Science in Mechanical Engineering, both from The Pennsylvania State University.