By Financial Compliance & Technology Desk
Published: June 2026
Executive Summary: The Death of the Visual Receipt
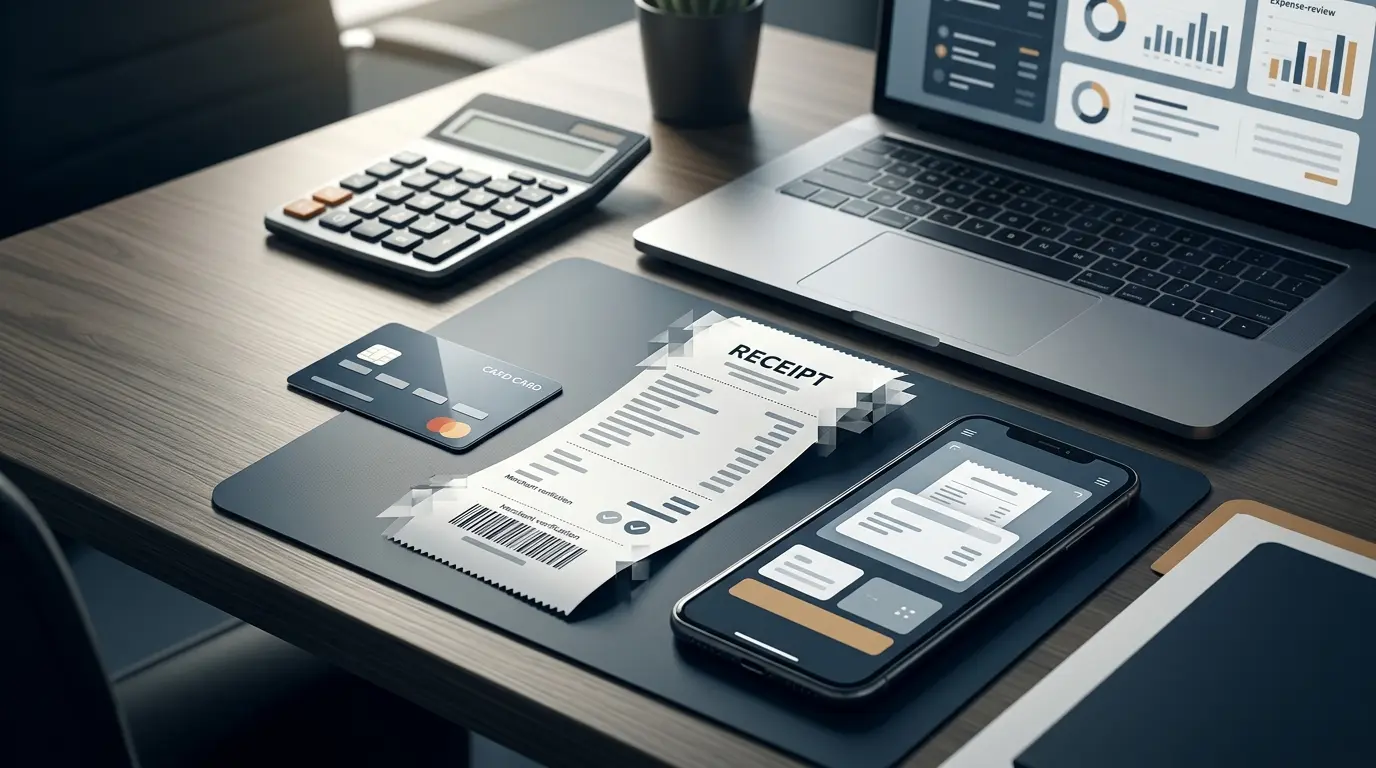
For decades, the foundation of corporate expense reimbursement rested on a simple, physical anchor: the paper receipt, later digitized as a PDF or a crisp smartphone photo. If an employee uploaded an image showing a legitimate merchant, a legible date, and a matching total, finance teams could generally check the box and issue a payout.
That foundational trust has suffered a near-fatal blow. According to recent platform data from expense-management vendor AppZen, AI-generated fake receipts now account for 70.8% of all flagged fraudulent expense submissions, surging dramatically from 0% in March 2025.
Simultaneously, a broad-based employee survey conducted by Emburse and Atomik Research reveals a startling willingness among everyday workers to leverage generative tools for financial gain. With AI models capable of instantly spinning up flawless, photorealistic invoices and itemized meal checks for any business in the world, the traditional visual-review workflow has become obsolete. For small businesses and enterprise finance teams alike, receipt verification is no longer an administrative bookkeeping task—it is a frontline cybersecurity and internal control issue.
1. Main Facts: The Scope of the Synthetic Fraud Epidemic
To understand the current crisis, finance leaders must look past sensational headlines and examine the hard data captured by compliance software and independent researchers between early 2025 and mid-2026.
The AppZen Platform Data
The 70.8% figure is derived from rigorous platform tracking by AppZen, which analyzed 1,471 AI-generated fake receipts flagged within its system. These fraudulent submissions originated from 745 individual employees distributed across 174 distinct companies, collectively attempting to extract $148,143 in fabricated reimbursements.
Crucially, experts emphasize that this percentage does not represent a new estimate of total workplace fraud across the entire global economy. Rather, it represents the dominant format of fraud among submissions that automated systems have already caught.
The Emburse Worker Survey
While automated platforms catch the slips that make it to the pipeline, workforce surveys reveal how widespread the temptation has become. An Emburse-commissioned survey of 2,000 U.S. and U.K. workers—conducted by Atomik Research—found that:
- 40% of U.S. respondents admitted to using AI to generate a fake business-expense receipt.
- 29% of U.K. respondents copped to the same practice.
Perhaps most alarmingly, access to the necessary technology is frictionless. Among the workers who admitted to generating synthetic receipts, 40% stated they used company-funded AI tools provided by their employers for daily workflows, while 9% built or customized their own tools specifically for financial circumvention.
2. Chronology: The Rapid Ascent of Generative Deception
The speed at which synthetic expense fraud evolved from a non-existent threat into a dominant mode of white-collar malfeasance underscores the explosive capabilities of modern generative artificial intelligence.
- March 2025: AppZen platforms recorded exactly 0% AI-generated receipts among flagged fraudulent submissions. At this stage, workplace expense fraud relied almost exclusively on legacy methods: altering digital PDFs with basic photo-editing software, modifying old paper receipts, or copying templates found on internet forums.
- Late 2025 to Early 2026: As large language models (LLMs) and advanced image-generation tools became universally accessible, free, and capable of rendering hyper-realistic text, textures, and merchant logos, the barrier to entry collapsed. Employees no longer needed graphic design skills to forge an invoice from a high-end restaurant or a boutique hotel.
- April 2026: A historic crossover occurred. According to AppZen’s tracking data, AI-generated fakes officially exceeded template-based fakes for the first time, establishing immediate dominance in the fraud landscape.
- May 2026: By mid-May, the share of AI-generated fakes skyrocketed to 70.8%, proving that bad actors adapt to technological advancements far quicker than traditional corporate compliance structures can react. Concurrently, data from the Emburse survey mapped out the psychological and behavioral shift occurring within standard office workforces.
3. Supporting Data & Behavioral Profiles
A deeper dive into the numbers reveals how employees are utilizing synthetic receipts, as well as the strategic sizing of fraudulent claims designed to slip beneath the radar of overworked finance departments.
Motivations and Intent
When researchers parsed the self-reported behavior of employees who admitted to creating fake receipts, distinct categories of risk emerged:
- Deliberate Fabrication (19%): These workers used AI to invent purchases that never actually happened—pocketing cash for ghost client dinners, fictitious travel, or phantom software subscriptions.
- Value Inflation (15%): These individuals attended a legitimate business lunch or booked a real hotel room, but used AI to inflate the actual total, banking the difference between the real bill and the submitted reimbursement.
- Lost Documentation (6%): A smaller subset admitted to using AI to recreate receipts for genuinely lost paperwork. While born of convenience rather than outright malice, this practice still violates compliance protocols, skews accounting records, and normalizes document falsification.
The Micro-Fraud Strategy: Avoiding the Audit Threshold
One of the most striking insights from the AppZen dataset involves the dollar value of the synthetic submissions.
- The average AI-generated fake receipt came in at roughly $100, with a median of just $32.
- By contrast, older template-based fakes tracked at an average of $182.
This discrepancy highlights a deliberate tactical pivot. Fraudsters are intentionally steering clear of massive, attention-grabbing claims that trigger multi-tier management approvals and forensic audits. Instead, they are deploying high-volume, low-dollar synthetic claims ($32 cab rides, $45 client coffees, $90 office supplies) that easily glide beneath automated corporate approval thresholds.
4. Official Responses & Industry Reactions
As compliance vendors, corporate executives, and fraud investigators grapple with the 71% reality, responses across the financial sector have been swift and uncompromising.
Expense-Management Vendors Sound the Alarm
Software developers who build the backend infrastructure for corporate spending are racing to update their detection algorithms. AppZen, Emburse, and competing platforms are shifting their focus away from static document aesthetics—such as checking if a logo looks crisp or if numbers align—toward dynamic, cross-platform validation.
Industry analysts point out that visual inspection is dead. A visually flawless receipt generated by Midjourney, DALL-E, or a dedicated invoice generator will effortlessly pass a human bookkeeper’s eyeball test every single time. Consequently, vendors are rolling out machine-learning filters designed to detect synthetic artifacts, unnatural font kerning generated by AI rendering engines, and metadata anomalies within uploaded image files.
Corporate Governance and HR Specialists
Human resources and legal departments are also scrambling. Corporate policies that once featured vague guidelines about "submitting accurate receipts" are being rewritten to explicitly address generative artificial intelligence. Companies are clarifying that using company-funded AI tools to fabricate financial documents is not a quirky administrative shortcut—it is an act of corporate fraud equivalent to embezzlement, carrying immediate termination and potential legal liabilities.
5. Implications for Businesses and Finance Teams
The rise of synthetic receipt fraud creates profound operational, accounting, and cultural consequences, particularly for small-to-medium-sized enterprises (SMEs) that lack expansive fraud-detection departments.
The Small Business Vulnerability
While large multinational corporations possess dedicated internal audit divisions, tiered authorization matrices, and advanced anomaly-detection software, small businesses operate under entirely different constraints.
In a typical SME, a single overworked office manager, bookkeeper, or business owner handles expense approvals alongside payroll, accounts payable, client scheduling, and vendor management. When presented with a stack of routine $32 reimbursement requests, these busy professionals rarely have the hours required to cross-examine every transaction. When spread across shared corporate cards, informal approval chains, and outsourced bookkeeping services, low-dollar synthetic claims can compound silently over months, draining capital without triggering alarms.
Long-Term Accounting and Tax Risks
The damage caused by synthetic receipts frequently outlives the initial payout. A fake, inflated, or misclassified receipt corrupts the integrity of a company’s financial ecosystem:
- Tax Records: Fabricated expenses distort profit-and-loss statements, creating compliance hazards during annual audits or IRS/HMRC reviews.
- Client Billing: If fictitious expenses are bundled into client project billings, it creates severe ethical and legal liability.
- Financial Modeling: Management teams relying on clean expense data to make strategic budgeting decisions are effectively flying blind when internal data is contaminated by synthetic fabrication.
6. Forward Outlook: How to Safeguard Your Expense Workflow
To survive the era of synthetic receipt fraud, organizations must modernize their internal controls. Relying on the visual appearance of an uploaded image is no longer a viable defense strategy. Finance teams should implement the following structural updates:
- Mandate Card-First Reconciliation: Whenever possible, tie expense submissions directly to corporate credit card transaction feeds. If an employee submits an AI-generated receipt for a dinner that never hit the company card ledger, the discrepancy is instantly exposed.
- Automated Merchant Cross-Checking: Implement verification tools that automatically cross-reference claimed merchant names and addresses against public business registries, geolocation data, and historical company spending patterns.
- Monitor Repeat Behaviors: Because synthetic fraud thrives on high-volume, low-dollar submissions, compliance software must flag patterns where the same employee repeatedly submits claims just below automated approval limits.
- Zero-Tolerance AI Policies: Establish unambiguous corporate policies regarding the use of generative AI tools for administrative paperwork, ensuring employees understand that synthetic fabrication carries severe disciplinary consequences.
Conclusion
The evolution of expense fraud from amateurish PDF edits to hyper-realistic, AI-generated synthetic documents marks a watershed moment in corporate finance. With over 70% of flagged fraudulent receipts now originating from generative tools—and nearly 40% of workers admitting a willingness to use them—the days of trusting a digital image at face value are over.
For small businesses and large enterprises alike, upgrading to data-driven, cross-verified expense controls is no longer an optional security enhancement. It is an absolute operational necessity for survival in a synthetic world.