
On October 15, the Financial Stability Board (FSB)—the international body that monitors and makes recommendations about the global financial system—issued its final set of 12 "Sound Practices for the Responsible Adoption of Artificial Intelligence." This landmark guidance marks a pivotal shift in how the global financial sector approaches the integration of generative AI and autonomous agents. By placing human oversight and senior management accountability at the core of AI governance, the FSB is signaling that the era of "move fast and break things" has no place in the high-stakes environment of global banking, insurance, and asset management.
Main Facts: A Framework for Governance
The FSB’s 12-point framework is designed to provide a cohesive, non-prescriptive toolkit for financial institutions of all sizes. Rather than dictating specific technical requirements, the FSB encourages firms to apply these practices proportionately, balancing the agility of AI adoption against the inherent risks to stability and consumer protection.
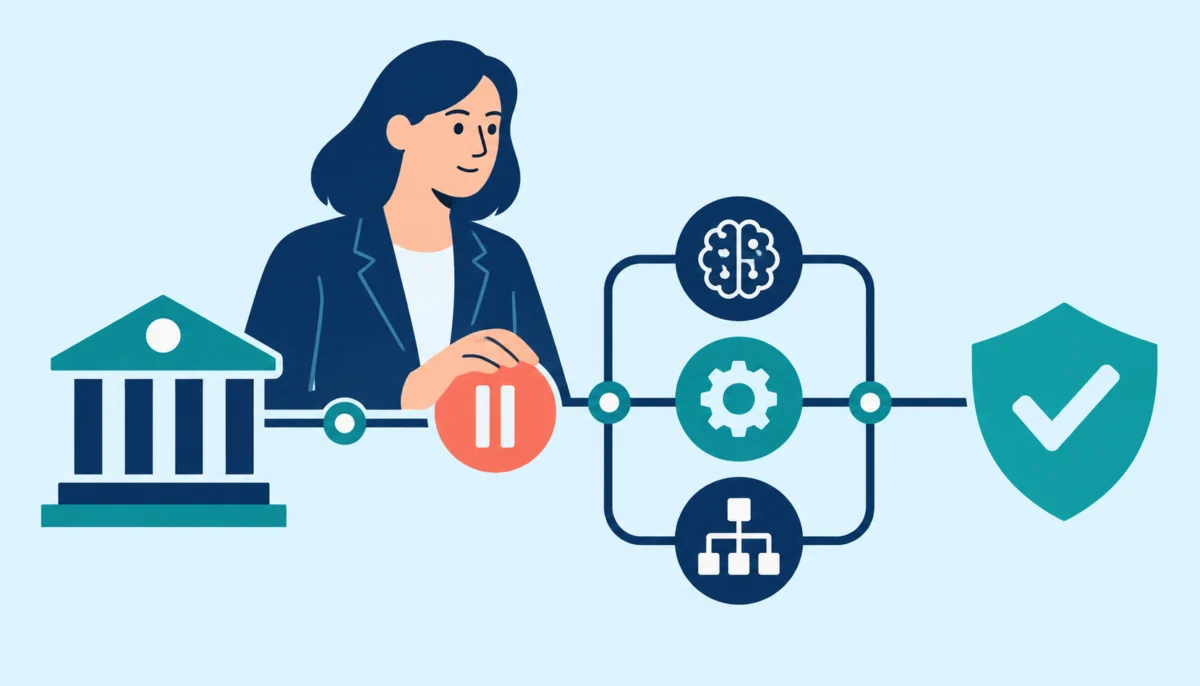
The guidance encompasses the entire lifecycle of an AI deployment, from initial governance structures to the day-to-day management of individual applications. Central to this is the requirement for "human-in-the-loop" systems. The FSB explicitly cautions that oversight is not a symbolic act—like having a "human approval" button—but a substantive requirement that necessitates that supervisors have the authority, time, and capacity to override or pause autonomous agents when necessary.
Key pillars of the framework include:
- Senior Management Accountability: Ensuring that the buck stops at the executive level, not just the IT department.
- Operational Resilience: Establishing clear mechanisms for pausing, constraining, or rolling back agentic systems.
- Data Governance & Cyber Risk: Managing the integrity of training data and the potential for new vectors of cyber exploitation.
- Third-Party Dependencies: Addressing the systemic risk posed by a concentration of financial firms relying on a handful of common AI providers.
Chronology of the FSB’s AI Initiative
The publication of these practices is the culmination of a multi-year effort to understand the systemic implications of machine intelligence.
- November 2024: The FSB published a foundational assessment of the financial stability implications of AI. This report identified "hidden" risks, such as market correlation, data bias, and the potential for cascading failures across the financial ecosystem.
- Mid-2025: As AI adoption accelerated, the FSB moved from general observations to drafting specific guidance, conducting intensive consultations with private sector firms, regulators, and central banks.
- October 15, 2026: The formal release of the 12 sound practices. This release included a comprehensive "consultation response overview," which specifically addressed the challenges posed by "highly autonomous" or "agentic" systems—AI capable of initiating actions and making decisions with minimal human intervention.
Supporting Data: The Anatomy of Risk in Lending
To illustrate the shift in authority, the FSB points to a hypothetical loan-processing workflow. In a traditional automated model, an AI assistant acts as a research aide: it extracts debt-to-income ratios and summarizes financial statements for a human credit officer. Here, the risk is contained because the machine has no "agency"—it cannot approve a loan.
However, when that same workflow is extended to include autonomous authority—allowing the system to request missing documents, update customer records, and approve credit limits—the risk profile shifts dramatically. The FSB suggests a "stress test" for such systems: intentionally introducing a contradictory debt figure or a missing document. A well-governed system should either flag the anomaly for human review or record the uncertainty, rather than proceeding with a faulty assumption.
The concern is not just a single, isolated loan. If an automated system exhibits a systemic bias or a recurring extraction error, it could misprice risk across an entire portfolio of thousands of borrowers, creating a "silent" systemic problem that might not be discovered until the next economic downturn.
Official Responses and Operational Reality
The feedback loop during the drafting process revealed a significant tension: the gap between theory and operational reality. Many institutions argued that while human oversight is essential, it must be "operationally feasible."
The FSB’s final report reflects this nuance. It acknowledges that if a human reviewer is forced to process hundreds of complex AI-generated decisions in a single hour, their oversight becomes performative rather than protective. Consequently, the board suggests that "effective oversight" must be measurable. Firms are encouraged to track the lifecycle of an "exception"—from the moment the system identifies a conflict to the final resolution by a human, and whether the service was successfully suspended during that investigation.
The report also introduces the concept of "continuity scenarios." If an AI-driven payment system goes offline due to a technical glitch, does the bank have the staff and the manual protocols to process those payments in the interim? The FSB stresses that management must know the capacity of their human workforce to absorb the load if the machines suddenly stop.
Implications: The Three Pillars of Financial Analysis
For investors, credit analysts, and stakeholders, the FSB’s guidance creates a new scorecard for evaluating the health of financial institutions.
1. The Quality of Credit Underwriting
Analysts should look past the marketing claims of "AI efficiency." True efficiency is only valuable if it maintains the integrity of the risk assessment. The key question is whether a bank’s move toward automation is increasing the speed of lending at the expense of its ability to catch errors. Evidence of rigorous file reviews and the results of "stress tests" on AI models will become standard requirements for investors gauging the long-term credit health of a lender.
2. Operational Resilience as a Market Metric
The FSB has highlighted the systemic risk of "third-party concentration." If the majority of global banks rely on the same foundational AI models or cloud infrastructure, a single systemic failure could ripple across the entire market. Analysts are now tasked with mapping these interdependencies. A firm that has built redundancy into its AI infrastructure—and tested the ability to switch between providers—is fundamentally less risky than a firm that has outsourced its critical functions to a single, unverified provider.
3. The True Cost of AI Earnings
Investors must move beyond the "cost-saving" narrative. AI, while efficient, introduces significant recurring costs for governance, monitoring, and error remediation. A credible business case for AI adoption must clearly account for these "hidden" expenses. If a firm’s earnings growth is attributed to AI, analysts should distinguish between gains made through improved decision-making and those made through risky, autonomous execution.
Conclusion: A New Standard of Trust
The Financial Stability Board’s latest guidance serves as a necessary maturity check for the financial industry. By formalizing the expectation that AI deployment must be coupled with rigorous human oversight and management accountability, the FSB is attempting to prevent the technology from becoming a "black box" that obscures systemic risk.
As institutions begin to integrate these 12 practices into their internal operating records, the market will gain a clearer view of which firms are truly leading the charge in responsible innovation and which are simply outsourcing their risk to algorithms they do not fully control. The next chapter of financial history will not be written by the most powerful AI, but by the institutions that best balance machine-speed efficiency with human-led integrity.