
The industrial landscape of the world’s second-largest economy is undergoing a profound structural shift. According to data released by China’s National Bureau of Statistics (NBS) on October 27, industrial profits across the country rose by 14.4% in September compared to the same period last year. This uptick brings the cumulative profit figure for the first nine months of the year to a formidable 6.03374 trillion yuan, representing a 15.5% increase on a comparable basis.
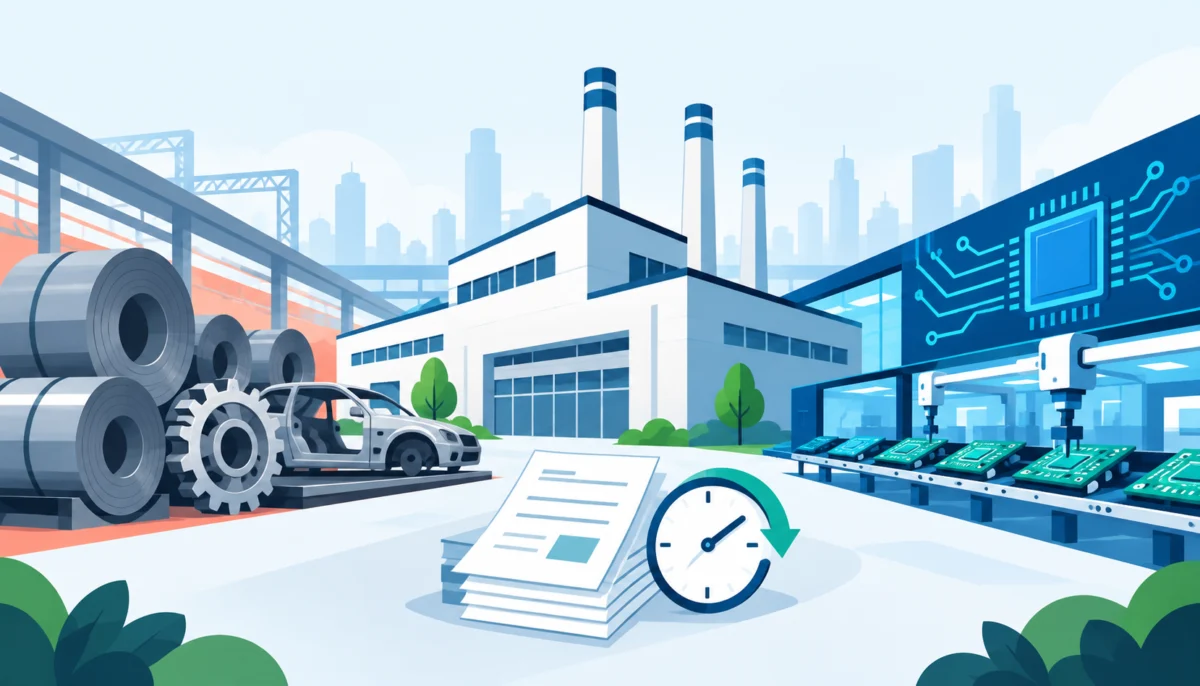
While the headline numbers suggest a robust expansion, a granular analysis reveals a stark divergence in fortune. The Chinese manufacturing sector is currently characterized by a "K-shaped" performance: while the electronics and high-tech sectors are enjoying a windfall, traditional heavy industries are grappling with significant earnings pressure. For international investors, corporate creditors, and supply chain managers, this distinction is not merely academic—it is a critical determinant of financial health and risk exposure.
Chronology and Momentum: Dissecting the Data
To understand the current state of China’s industrial health, one must look beyond the monthly headlines. September’s 14.4% year-on-year increase marks a significant rebound from August, which saw a more modest 4.2% gain. The NBS attributed the August slowdown partly to a "high comparison base," a common phenomenon where year-on-year growth appears dampened because it is measured against an exceptionally strong period from the previous year.
However, the picture becomes more nuanced when examining the cumulative data. For the first eight months of the year, the cumulative profit growth rate stood at 15.7%. By the end of September, this rate had moderated slightly to 15.5%. This slight decline in the nine-month average, despite the strong monthly performance in September, underscores the volatility inherent in industrial reporting.
The NBS data serves different analytical functions:
- The Monthly Snapshot: Provides insight into immediate, short-term momentum and the impact of recent policy or market shifts.
- The Cumulative Rate: Offers a smoothed view of performance, mitigating the impact of monthly anomalies and reflecting the broader trajectory of the fiscal year.
Analysts caution that reading one as a substitute for the other provides an incomplete narrative. Furthermore, these year-on-year figures are not seasonally adjusted. Factors such as the timing of holidays, variations in production schedules, and base effects can lead to distortions. A truly "durable" recovery, according to financial observers, will only be confirmed when multiple consecutive reports show broad-based earnings growth supported by tangible cash inflows and consistent order books.
Diverging Destinies: The High-Tech vs. Traditional Split
The most striking aspect of the latest NBS report is the widening chasm between industry sectors. The nine-month data paints a vivid picture of this disparity:
- Electronics Dominance: Profits in computer, communication, and other electronic equipment manufacturing skyrocketed by 103.8%. This surge is largely fueled by global demand for AI-integrated hardware, semiconductors, and high-end consumer electronics.
- The Industrial Drag: Conversely, auto manufacturing profits fell by 22.8%, while the ferrous-metal smelting and rolling sector—a traditional pillar of the Chinese economy—plunged by 73.3%.
For a lender, this spread is a critical indicator. A supplier embedded in the electronics value chain may be experiencing unprecedented liquidity and growth, while a peer in the steel or automotive component sector may be struggling to maintain basic solvency. The national aggregate obscures the reality of individual firm performance; creditors must look past industry averages to assess the specific order patterns, negotiating power, and financing needs of the borrower in question.
The Mirage of Output: Production, Prices, and Margins
A common pitfall in assessing industrial health is conflating production volume with profitability. The NBS reported that industrial value added rose by 5.5% in real terms in September, up from 5.2% in August. While this confirms that factory floors are indeed busier, it does not guarantee that these activities are generating superior margins.
The relationship between factory-gate prices and input costs further complicates the picture. September saw factory-gate prices rise 5.0% year-on-year, while industrial purchasing prices climbed 6.9%. Because these indexes cover different "baskets" of goods, they cannot be used as a simple margin calculator for any single manufacturer.
A firm may see rising demand for its finished products, but if its energy and raw material costs are rising at a faster clip—and if the firm lacks the "pricing power" to pass these costs onto the consumer—profitability will inevitably suffer. Analysts are therefore looking for company-level data: What are the specific contractual terms? How long are the lead times for input procurement? Does the firm have the flexibility to hedge against commodity price volatility? Without these specifics, high output growth remains a misleading proxy for financial success.
Cash Conversion and the Receivables Challenge
As of the end of September, industrial firms reported a staggering 29.77 trillion yuan in accounts receivable, a 10% year-on-year increase. More importantly, the average collection period for these receivables reached 71.6 days—an increase of 1.3 days compared to the same period last year.
This lengthening collection period is a red flag for liquidity. In a healthy cycle, an increase in receivables might simply reflect rising sales. However, when the collection period stretches, it suggests that firms are finding it harder to convert sales into actual cash. This puts a strain on working capital, forcing companies to increase borrowing to cover payroll, interest payments, and essential operational expenses.
For a supplier, this highlights the necessity of "invoice aging" analysis. If a company is expanding rapidly but its cash conversion cycle is deteriorating, it may face a liquidity crisis even while its P&L statement shows paper profits. Lenders are advised to stress-test their borrowers by modeling scenarios where collection periods continue to extend, ensuring that the borrower’s credit facilities are sufficient to bridge the gap between delivery and payment.
Strategic Implications for Stakeholders
The latest NBS release serves as a foundational document for three distinct groups of stakeholders, each requiring a different analytical lens:
1. For Corporate Creditors
The primary mandate is to separate earnings strength from cash generation. A borrower in a "hot" sector like electronics may appear safe, but if they are over-leveraged to fund rapid capacity expansion, they remain vulnerable to a cyclical downturn. Creditors should scrutinize the maturity of working-capital debt and demand transparency regarding customer concentration. Relying on sector averages is insufficient; the focus must remain on the specific solvency of the individual entity.
2. For Market Participants
Investors must distinguish between broad economic recovery and sectoral strength. Portfolios overly concentrated in the electronics supply chain may be subject to common risks—such as component shortages or shifts in global tech policy—that the aggregate national data fails to capture. It is essential to compare these exposures against the realities of weaker manufacturers to determine if the "recovery" is truly systemic or merely a localized surge in high-tech demand.
3. For Country Risk Analysis
While the September improvement is a welcome signal, it does not yet constitute evidence of a self-sustaining industrial engine. Observers must monitor whether these profit gains translate into tangible tax revenue and sustainable fixed-asset investment. Currently, manufacturing fixed-asset investment is down 2.1% year-on-year, with spending highly concentrated in the electronics sector. This selective investment suggests that companies are cautious about the broader economic environment.
Final Assessment: A Call for Granular Vigilance
The September data is a testament to the resilience of China’s high-tech manufacturing sector, but it is not a "rising tide" that lifts all boats. The divergence between the surging electronics industry and the struggling traditional sectors indicates that the economy is undergoing a painful but necessary transition.
For those engaging with the Chinese market, the lesson is clear: the era of relying on broad industrial growth as a proxy for safety is over. Future success will be predicated on the ability to distinguish between companies that are capturing value through technological innovation and those that are merely struggling to survive in a high-cost, low-margin environment. As we look toward the next quarter, the focus must remain on cash flow, debt maturity profiles, and the ability of firms to navigate a tightening liquidity environment. The headline numbers may be impressive, but the real story is written in the details of the balance sheet.