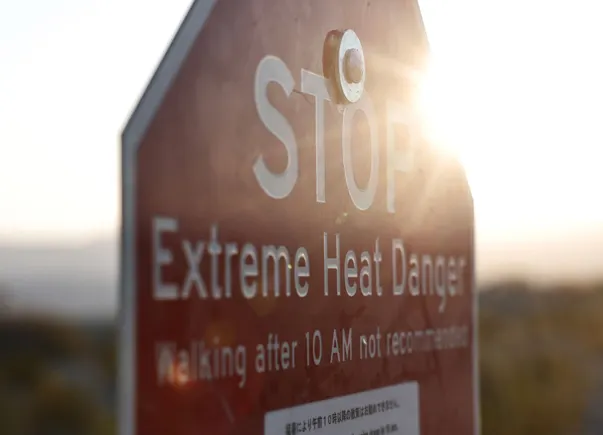
As global temperatures continue to shatter historical records, the manufacturing backbone of the modern world is facing an unprecedented and often invisible adversary: extreme heat. A landmark industry survey released Tuesday by the Global Electronics Association reveals that electronics manufacturers worldwide experienced severe, widespread supply chain disruptions this year directly linked to extreme weather conditions. From assembly plants in Asia to distribution hubs in North America and Europe, the intersection of rising atmospheric temperatures and industrial output has created a complex web of logistical challenges.
While the semiconductor shortage of the early 2020s and pandemic-era port congestion are fresh in the memories of industry executives, the latest data suggests that climate change is introducing a permanent, recurring threat vector to global commerce. According to the trade association’s findings, nearly half of all surveyed manufacturers point to extreme heat as a primary catalyst for operational bottlenecks, redefining how companies must approach resilience, risk management, and long-term infrastructure planning.
Main Facts
The Global Electronics Association’s sentiment report highlights the profound vulnerability of high-tech manufacturing ecosystems to environmental stress. The core findings outline a systemic disruption across international borders:
- Supplier Delivery Disruptions: Nearly 50% of electronics manufacturers globally—spanning North America, Europe, and the Asia-Pacific region—cited supplier fulfillment and delivery delays as the single most severe impact of this year’s heat waves.
- Widespread Exposure: More than half of all manufacturers worldwide reported that their supply chains were exposed to severe heat-related disruptions. In North America specifically, 47% of firms reported direct exposure, with over 40% indicating they were somewhat or slightly exposed, and 6% reporting high exposure.
- Impact on Throughput and Productivity: Over 80% of global manufacturers who faced heat-related disruptions reported negative consequences concerning their operational productivity and output capacity. In North America, 13% noted major impacts, while 50% reported moderate production setbacks.
- Growing Anxiety Among Unaffected Firms: Even among North American companies that avoided direct heat disruptions this year, 57% reported minor-to-no issues, but anxiety regarding future vulnerabilities remains exceptionally high.
- Future Outlook: Looking ahead, more than two-thirds of manufacturers globally expect extreme heat to drive interruptions in productivity and operational throughput in the coming years.
Chronology and Context: The Escalation of Climate-Induced Industrial Friction
To understand how extreme heat has transformed from a localized discomfort into a macro-economic supply chain crisis, it is necessary to examine the timeline of industrial vulnerability over the past decade.
The Pre-2020 Era: Ignoring Environmental Baselines
Historically, industrial supply chain management focused heavily on labor arbitrage, geopolitical stability, transportation costs, and lean inventory strategies (such as just-in-time manufacturing). Environmental risks were largely categorized into acute, catastrophic events—such as hurricanes, earthquakes, and major floods—that caused sudden, catastrophic damage. Gradual environmental stressors, such as steadily rising summer baseline temperatures, were routinely absorbed by standard facility HVAC systems without altering strategic logistics forecasts.
The Pandemic Shock and Infrastructure Stress (2020–2023)
The COVID-19 pandemic exposed the fragility of global supply networks. As manufacturing plants reopened, they did so against a backdrop of accelerating climate anomalies. Record-shattering heat waves across Europe, North America, and parts of Asia began to strain power grids and test the physical limits of factory machinery. However, these incidents were frequently viewed by analysts as anomalies rather than systemic shifts, overshadowed by immediate logistical failures like port congestion and chip shortages.
The Turning Point: The 2026 Sentiment Survey
By the summer of 2026, the cumulative toll of sustained high temperatures prompted the Global Electronics Association to formally quantify the impact through its comprehensive trade survey. Released in September 2026, the data established that extreme heat is no longer a peripheral concern. It is now recognized as a primary operational hazard that actively erodes manufacturing margins, delays product launches, and destabilizes delicate component-sourcing schedules.
Supporting Data: Dissecting the Regional and Operational Impacts
The survey data provides a granular look at how heat manifests as a destructive force within electronics manufacturing. While the survey did not ask respondents to isolate the exact micro-causes of supplier delays, industry experts note that extreme heat triggers a cascade of compounding failures throughout the logistics chain.
The Anatomy of Supplier Delays
Chief Economist Shawn DuBravac, in an interview with Supply Chain Dive, explained that the pervasive supplier delays reported by 50% of global manufacturers are likely the symptom of multiple intersecting pressures.
"My sense is that it was probably an assortment of different things that would fall under that broader category of supplier delays," DuBravac noted.
These underlying factors include:
- Labor Constraints: Extreme heat degrades worker productivity, increases safety risks, and frequently leads to mandated rest breaks, reduced shift durations, or elevated absenteeism.
- Factory-Level Stressors: Precision electronics manufacturing—particularly cleanroom environments required for semiconductor packaging and circuit board assembly—demands strict temperature and humidity controls. When ambient temperatures soar, cooling systems frequently reach their thermal limits, forcing unplanned facility shutdowns or reduced operating speeds.
- Freight and Transportation Bottlenecks: Road, rail, and maritime logistics are heavily impacted by extreme heat. Asphalt deformation slows trucking, railway tracks can warp under extreme solar radiation (necessitating speed restrictions), and barge shipping on inland waterways is frequently disrupted by low water levels resulting from heat-induced drought.
North American Exposure and Anticipated Bottlenecks
In North America, the distribution of disruption severity revealed a mixed baseline. While 57% of respondents reported no disruptions, and 20% experienced only minor issues, the remaining firms felt acute pressure. Moderate and major interruptions were each cited by 6% of North American respondents.
For firms that managed to escape unblemished, apprehension remains high. Among North American companies anticipating future challenges, the primary concerns are sharply defined:
- Operating Constraints (29%): Facilities worry about hitting thermal ceilings, where internal cooling infrastructure fails to maintain the safe operating temperatures required for sensitive electronics fabrication.
- Power Reliability Issues (29%): Surging demand for residential and commercial air conditioning places immense stress on regional electrical grids. This results in rolling brownouts, grid curtailments, and forced power-rationing agreements that directly impact energy-intensive manufacturing plants.
- Secondary Logistical Failures (17%): Companies cited worries regarding transportation delays, unplanned equipment downtime, and upstream supplier delivery failures.
- Minor Concerns (Single Digits): A smaller percentage of firms expressed anxiety over customer demand disruptions, missed shifts, reduced staffing levels, and product quality defects.
When asked to quantify the operational toll, over 50% of global manufacturers reported exposure to severe heat disruptions. In North America, 47% reported exposure, split between 6% experiencing high exposure and over 40% experiencing slight-to-moderate exposure. Looking forward, 32% of North American firms anticipate minor impacts in upcoming years, while 14% expect moderate-to-major disruptions.
Official Responses and Industry Insights
As the data makes clear, the electronics sector is navigating uncharted waters. Industry leaders and economic analysts are calling for a fundamental shift in how manufacturing resilience is measured and maintained.
Shawn DuBravac emphasized that passive observation is no longer a viable strategy for supply chain executives. According to DuBravac, the definition of a "moderate impact" goes far beyond a minor inconvenience.
"To me, a moderate impact would be something that has to be addressed, something that impacted throughput, that impacted production schedules," DuBravac explained.
When production schedules slip due to heat-induced slowdowns, the downstream ripple effects can jeopardize holiday product launches, corporate earnings targets, and long-term customer relationships. To mitigate these risks, industry advocates stress that traditional contingency planning must evolve to explicitly incorporate meteorological stress tests.
Strategic Implications: The Playbook for Climate Resilience
The overarching takeaway from the Global Electronics Association’s findings is that proactive planning is essential for industrial survival in a warming world. Furthermore, industry experts suggest that the optimal time to enact these defenses is not during the height of a blistering summer, but rather during the cooler transitional months of autumn.
Shifting the Window for Strategic Preparation
Fall offers a critical window of operational calm. Temperatures drop, facilities experience reduced cooling loads, and logistics networks temporarily stabilize. DuBravac advises manufacturers to utilize this seasonal reprieve to stress-test their operational readiness.
"If I were advising a manufacturer, I would tell them now is the perfect time to run scenario plans on what happens to your operations if you had a week of 110-degree weather, if you had two weeks of 110-degree weather, if you had three weeks of 110-degree weather," DuBravac recommended. "You want to have a clear playbook that you can turn to, rather than having to write the rules while you’re in the midst of it."
Key Pillars of a Heat-Resilient Manufacturing Strategy
To safeguard electronics supply chains against future thermal extremes, executives are beginning to invest in several core areas:
- Infrastructure Hardening: Upgrading HVAC and industrial cooling systems well beyond historical baselines. Facilities are investing in redundant cooling capacity and advanced thermal management materials to protect sensitive cleanrooms and equipment.
- Energy Independence and Microgrids: To counter the threat of grid curtailments and brownouts, forward-thinking manufacturers are integrating on-site renewable energy generation (such as solar arrays) coupled with industrial-grade battery storage systems, ensuring uninterrupted operations during peak grid stress.
- Supplier Diversification and Geographic Mapping: Geographic concentration is a primary vulnerability. Companies are mapping their Tier-1, Tier-2, and Tier-3 suppliers against climate risk indices, ensuring that critical component sourcing is not overly reliant on regions prone to chronic, unmitigated extreme heat.
- Flexible Workforce Policies: Designing labor protocols that prioritize worker safety and productivity without grinding production to a halt—such as shifting intensive assembly shifts to cooler night hours, upgrading worker hydration stations, and automating heat-exposed material handling tasks.
Conclusion
The 2026 Global Electronics Association survey serves as a definitive wake-up call for the high-tech manufacturing sector. Extreme heat is no longer merely a weather phenomenon; it is a quantifiable, material risk factor that directly impacts global supply chain velocity, operational throughput, and corporate profitability. As climate patterns continue to intensify, the distinction between resilient enterprises and vulnerable ones will be defined by the quality of the playbooks written today, during the cooling quiet of autumn, before the next wave of extreme heat tests the limits of global production.