
Financial analysts and global market observers are closely monitoring a period of intense volatility, marked by a significant resurgence of the Japanese Yen, ongoing disruptions within the global technology supply chain, and sudden fluctuations in the artificial intelligence (AI) hardware market. These concurrent economic shifts have forced central banks, investors, and industry leaders to reassess growth forecasts and risk management strategies worldwide.
Executive Summary: A Convergence of Economic Pressures
Global financial markets have entered a phase of heightened unpredictability, driven by a rare convergence of macroeconomic pressures. At the center of this turbulence is the sudden and robust recovery of the Japanese Yen against the US dollar and other major currencies, defying months of downward pressure.
Simultaneously, the technology sector—long the engine of post-pandemic global economic growth—is facing acute structural adjustments. Widespread supply chain bottlenecks, combined with a dramatic correction in the valuation and production metrics of artificial intelligence (AI) hardware components, have triggered a ripple effect across international exchanges. Economists note that these developments are not isolated incidents; rather, they reflect a broader recalibration of investor sentiment as markets transition away from hyper-growth expectations toward defensive positioning.
Chronology of Market Events
To understand the current financial landscape, it is essential to trace the sequence of events that culminated in this multi-front market correction:
- Early Q1: Persistent inflation concerns and shifting interest rate expectations in major economies led to sustained volatility in currency markets. The Japanese Yen hovered near multi-decade lows, placing immense pressure on Japanese monetary authorities to consider intervention.
- Mid-Quarter Policy Shifts: Speculation mounted regarding potential adjustments to the Bank of Japan’s (BoJ) ultra-loose monetary policy framework, sparking early algorithmic trading spikes in Tokyo.
- The Technology Correction Phase: Reports from key Asian manufacturing hubs highlighted unexpected slowdowns in semiconductor fabrication lines, specifically impacting high-end AI processing units and specialized logic chips.
- The Yen’s Turning Point: A coordinated shift in macroeconomic data releases triggered a massive short-covering rally in the Yen, catching leveraged institutional investors off guard and forcing rapid portfolio liquidations across global equities.
- Current State: Markets continue to digest the implications of a stronger Yen intersecting with constrained AI hardware supplies, leading to a cautious, defensive trading posture among institutional asset managers.
Supporting Data and Currency Market Dynamics
The magnitude of the recent shifts is best illustrated by quantitative indicators across foreign exchange and equity markets:
Foreign Exchange Movements
The Japanese Yen staged a dramatic reversal, appreciating past critical technical resistance levels. Market data shows the currency climbing toward the 157.66 per US dollar threshold following months of steady depreciation. This movement forced foreign exchange desks to re-evaluate short positions that had dominated trading strategies for the better part of the fiscal year.
Furthermore, trade-weighted indices indicate that the Yen’s recovery has broader implications for export-driven economies in East Asia. Analysts point out that while a weaker currency previously favored Japanese multinational corporations by boosting overseas repatriation values, the sudden reversal introduces margin compression risks for firms that failed to hedge against rapid currency fluctuations.
Equity and Bond Market Reactions
Parallel to the currency shift, global bond yields experienced notable compression as capital flowed rapidly into safe-haven assets. Sovereign debt yields in major Western markets retreated as institutional investors sought refuge from equity volatility.
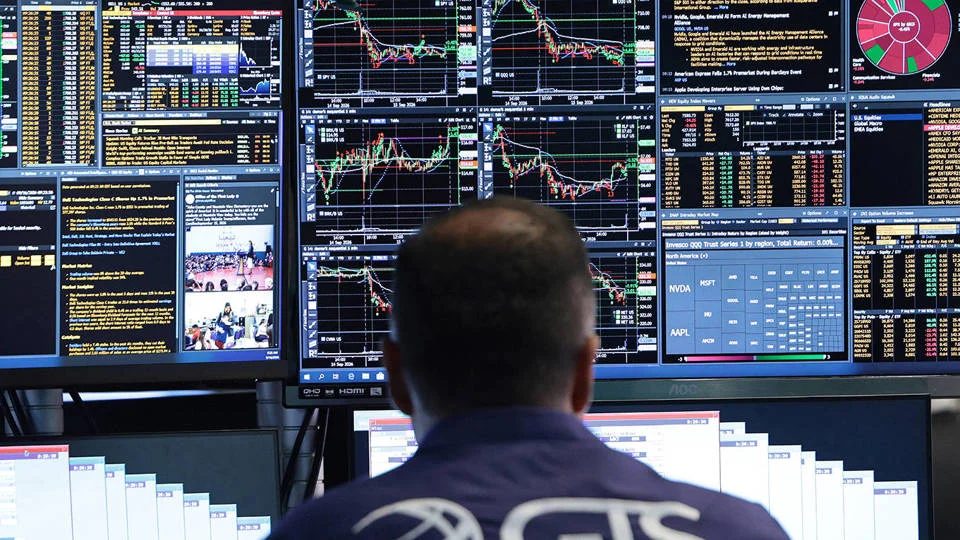
Equity benchmarks with heavy weightings in technology and semiconductor manufacturing saw intraday swings exceeding historical averages. Trading volumes surged by over 25% across key Asian exchanges as algorithmic trading systems reacted to breaking economic data and revised corporate guidance.
The AI Hardware Turmoil: Boom Meets Bottleneck
Perhaps the most disruptive element of the current economic cycle is the turbulence observed within the artificial intelligence hardware ecosystem. For the past several years, the insatiable demand for generative AI models, large language frameworks, and machine learning infrastructure fueled an unprecedented boom in semiconductor manufacturing.
However, recent supply chain audits reveal that the sector is hitting physical and logistical ceilings. Key manufacturers of advanced graphics processing units (GPUs) and application-specific integrated circuits (ASICs) have encountered severe production bottlenecks. These constraints stem from a combination of raw material shortages, high capital expenditure requirements for next-generation fabrication plants, and yield issues with cutting-edge 3nm and 2nm wafer nodes.
Impact on Tech Valuations
The realization that AI hardware supply cannot instantly scale to meet projected demand has forced a reality check among tech-heavy indices. Companies that built aggressive capital expenditure models around guaranteed access to high-performance AI chips are now facing delivery delays extending into multiple quarters. Consequently, market valuations for several major technology conglomerates have experienced downward revisions, pulling broader market indexes down with them.
Industry analysts emphasize that this is not a collapse of the AI thesis itself, but rather a painful maturation process. The market is moving away from speculative exuberance toward disciplined, efficiency-driven deployment of computational resources.
Official Responses and Central Bank Interventions
In the wake of these simultaneous disruptions, central banks and regulatory bodies have stepped up monitoring and communication efforts to reassure investors.
The Bank of Japan’s Stance
Monetary authorities in Tokyo have maintained a cautious dialogue with financial markets. While resisting direct, unannounced currency interventions, officials have repeatedly signaled that excessive and disorderly movements in the foreign exchange market are undesirable. The BoJ’s ongoing deliberations regarding interest rate normalization have become the focal point for global macroeconomic strategists, who are parsing every statement from bank leadership for clues about future policy tightening.
Global Regulatory Coordination
International financial bodies, including the International Monetary Fund (IMF) and regional central bank committees, have issued advisory notes urging commercial financial institutions to enhance their liquidity buffers. Regulators are particularly focused on cross-border exposures tied to leveraged tech sector investments and carry-trade unwinding.
An official statement released by a coalition of financial stability monitors noted: "The intersection of rapid currency realignments and capital-intensive technology cycles requires heightened vigilance from market participants. Risk management frameworks must account for non-linear shocks that can propagate rapidly across interconnected global markets."
Economic Implications and Future Outlook
As the dust begins to settle on the initial wave of volatility, economists and market strategists are outlining the medium- to long-term implications of these events:
- Redefining Corporate Hedging Strategies: Multinational corporations operating in both manufacturing and services sectors are overhauling their foreign exchange and supply chain risk management policies. Relying on historical currency correlations is no longer viewed as a viable strategy.
- Rationalization of AI Investments: The hardware crunch is expected to filter out speculative, underfunded AI startups while rewarding firms with secured, long-term supply contracts and proprietary efficiency software. Capital will likely concentrate on proven infrastructure providers rather than early-stage exploratory ventures.
- Monetary Policy Divergence: As Japan moves closer to exiting its decades-long era of ultra-low interest rates while other major economies contemplate easing cycles, global capital flows will experience structural realignments. This divergence will continue to drive currency volatility through the remainder of the fiscal year.
- Supply Chain Resiliency: The semiconductor industry is accelerating its diversification efforts, investing heavily in redundant manufacturing hubs outside traditional geopolitical hotspots to insulate against future supply shocks.
Conclusion
The current financial environment underscores the fragile interconnectedness of modern global economics. The simultaneous strengthening of the Japanese Yen and the structural correction within the AI hardware market serve as a reminder that rapid technological expansion must eventually navigate the laws of macroeconomic gravity. For investors, policymakers, and industry leaders, adaptability, rigorous risk assessment, and a focus on fundamental operational efficiency will remain paramount as these market dynamics continue to evolve.
Source: Economic Today Analysis Desk