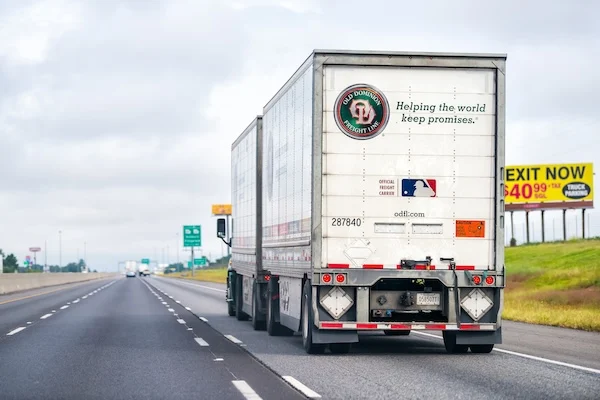
THOMASVILLE, N.C. – Old Dominion Freight Line (ODFL), a titan in the national less-than-truckload (LTL) shipping sector, has released its operating metrics for August, signaling a period of robust financial performance defined by strategic yield management. Despite a slight dip in overall tonnage, the carrier’s ability to command higher rates has underscored its resilience in a complex macroeconomic environment.
As the transportation industry navigates the tailwinds of an industrial recovery and the headwinds of consumer uncertainty, Old Dominion’s latest disclosures provide a granular look at how a premium carrier maintains profitability while preparing for a long-term surge in infrastructure-related demand.
Main Facts: A Snapshot of August Performance
For the month of August, Old Dominion reported a 12.5% year-over-year increase in revenue per day. This performance was primarily driven by a significant rise in LTL revenue per hundredweight—a critical metric reflecting the pricing power of the carrier.
However, the revenue gains were tempered by a modest decline in volume. The company noted a 0.9% decrease in LTL tons per day. A deeper look at the data reveals that this contraction was the result of a 2.4% decrease in daily shipments, which was partially offset by a 1.7% increase in the weight per individual shipment. This suggests that while Old Dominion is handling fewer total shipments, the shipments they are processing are heavier and, consequently, more lucrative under the company’s current yield-focused strategy.
On a quarter-to-date basis, the trend remains consistent. LTL revenue per hundredweight has climbed 11.3% annually. Even when stripping out the volatility of fuel surcharges, the underlying yield—revenue per hundredweight excluding fuel—increased by 4.8%. These figures highlight a carrier that is prioritizing margin expansion over the pursuit of low-margin volume, a strategy that sets it apart from more aggressive competitors.
Chronology of Growth: From Q2 Success to August Stability
To understand the current trajectory, one must look at the foundation laid in the second quarter of the fiscal year. ODFL reported second-quarter revenue of $1.55 billion, an impressive 10.4% increase over the previous year. Within this total, LTL services revenue accounted for $1.538 billion, reflecting a 10.3% annual gain.
This sustained momentum through July and August confirms that the demand trends observed in the spring have persisted into the late summer. While the broader transportation sector often experiences cyclical volatility, Old Dominion’s consistency has been a hallmark of its recent reporting.
The company’s leadership attributes this performance to a “best-in-class” service proposition. By maintaining high-quality service levels, Old Dominion has managed to insulate itself from the price wars that often plague the LTL sector. As the company moves through the third quarter, the data suggests that the internal systems—capacity, labor, and technology—are operating in alignment with the company’s long-term strategic plan to secure profitable market share.

Supporting Data: Dissecting the Metrics
The delta between "tons per day" and "revenue per hundredweight" is the central narrative of Old Dominion’s recent performance. In logistics, volume is vanity, but yield is sanity.
- Yield vs. Volume: The 12.5% growth in revenue per day against a 0.9% decline in tonnage is a clear indicator of successful rate management. By focusing on heavier shipments, the company is optimizing its trailer space and labor hours, effectively generating more revenue from the same physical footprint.
- The Fuel Factor: With the 11.3% increase in revenue per hundredweight (inclusive of fuel) compared to the 4.8% increase (exclusive of fuel), it is evident that fuel surcharges remain a significant component of the pricing structure. However, the 4.8% "clean" growth demonstrates that even without the inflationary pressure of fuel prices, the base pricing power of Old Dominion remains strong.
- The Industrial Pulse: Industry-wide data, including the Institute for Supply Management’s (ISM) Manufacturing Report on Business, supports the narrative of an industrial rebound. As manufacturing activity stabilizes and begins to expand, LTL carriers—which specialize in the movement of industrial parts, components, and raw materials—are the primary beneficiaries.
Official Responses: The Leadership Perspective
Marty Freeman, President and Chief Executive Officer of Old Dominion, expressed confidence in the company’s path forward. In a statement accompanying the August metrics, Freeman emphasized that the company’s consistency is no accident.
“Old Dominion produced solid revenue growth for July and August, with underlying demand trends remaining relatively consistent as the quarter has progressed,” Freeman noted. “In addition, the strength and consistency of our industry-leading service continue to support the ongoing improvement in our LTL revenue per hundredweight.”
Freeman’s commentary underscores a commitment to the “Old Dominion way”—a strategy that eschews rapid, volume-heavy growth in favor of sustainable, margin-focused development. By keeping “all the necessary elements of capacity in place,” the company is ensuring that it does not experience the service degradation that often occurs when carriers grow too quickly for their infrastructure to handle.
“Our value proposition remains best-in-class,” Freeman added. “We remain confident that through the continued execution of our long-term strategic plan, we are well positioned to win profitable market share and increase shareholder value over the long term.”
Implications: The Road to 2027
The implications of Old Dominion’s performance extend far beyond the monthly balance sheet. Industry analysts are interpreting these figures as a bellwether for the broader U.S. economy, particularly regarding the intersection of industrial recovery and infrastructure investment.
The Industrial/AI Nexus
Baird analyst Daniel Moore, in a recent research note, pointed out that ODFL’s August metrics exceeded expectations. Moore argues that the carrier’s success is direct evidence of a “continued improvement in the LTL freight market led by an industrial recovery.”
Perhaps more compelling is Moore’s outlook on the AI infrastructure build-out. He posits that LTL volume demand should see a structural improvement through 2027 as massive data center and semiconductor facility projects transition from the planning phase to the construction and completion phase. This transition will require the movement of specialized equipment and building materials, a task for which the LTL industry—and Old Dominion specifically—is uniquely suited.

The Retail and Macroeconomic Paradox
While the industrial sector provides a tailwind, the consumer sector remains a wildcard. Retail sales and consumer-driven LTL demand continue to face a "mixed" outlook. High fuel prices—exacerbated by the ongoing conflict in Iran—continue to weigh on consumer confidence. Furthermore, the LTL sector is not immune to broader economic pressures, including:
- Tariff and Trade Uncertainty: The evolving geopolitical landscape continues to create friction in global supply chains.
- Inflationary Pressures: While ODFL is passing along costs through higher rates, inflation continues to drive up operational expenditures, including maintenance, real estate, and insurance.
- The Employment Outlook: The competition for skilled labor, particularly Class A drivers, remains a constant challenge that necessitates continuous investment in employee retention and wage competitiveness.
The "Differentiated Strategy"
Analysts frequently point to a major divide in the LTL market: the "Growth-at-All-Costs" carriers versus the "Yield-Disciplined" carriers. Old Dominion is firmly in the latter camp.
As Moore wrote, “It remains clear to us that ODFL remains highly disciplined on yield and focused on earning incremental margin, a differentiated strategy relative to more growth-focused peers that have emphasized volume.” This disciplined approach serves as a defensive moat; in times of economic tightening, the company is less exposed to the risks of over-leverage or service dilution, while in times of expansion, its high-margin base allows for greater profitability.
Conclusion: A Barometer for the Future
The August performance of Old Dominion Freight Line serves as a masterclass in modern logistics management. By successfully navigating the tension between volume and yield, the company has proven that it can thrive even when the broader economic indicators are mixed.
As the U.S. economy continues its slow climb toward a more manufacturing-heavy future—driven by AI infrastructure, onshoring, and energy projects—Old Dominion appears well-positioned to maintain its status as a market leader. The company’s focus on long-term value creation, supported by its "best-in-class" service promise, suggests that its current trajectory is not merely a short-term success, but a sustainable model for the evolving transportation landscape.
For stakeholders, the message is clear: Old Dominion is not just reacting to the market; it is actively shaping its role within it, choosing the path of profitable growth over the volatility of volume. As the calendar turns toward the final months of the year, the industry will be watching to see if this disciplined strategy continues to yield the dividends that both leadership and shareholders have come to expect.