By Nancy Qian
October 12, 2026
CHICAGO — For at least a generation, China’s extraordinary "economic miracle" allowed its citizens to look across the Pacific not at the inhabitants of a wealthier, unreachable world, but at potential peers. The decades-long march of urbanization, industrialization, and skyrocketing incomes fostered a collective belief that the future belonged to Beijing.
Yet, today, the two societies have become peers in a far more sobering sense. The Chinese public is increasingly suffering the same rude awakening that Americans did when their own post-war economic miracle sputtered and ended, leaving behind a landscape of dashed expectations, structural unemployment, and deep-seated anxiety about the future.
Main Facts: The End of Uninterrupted Growth
The fundamental shift defining contemporary China is the transition from a mindset of boundless upward mobility to one of stagnation and contraction. For most of the past forty years, China’s trajectory was defined by a singular, upward vector: everything was moving forward, and tomorrow was guaranteed to be materially better than today.
Today, however, the structural pillars that drove that unprecedented expansion—debt-fueled real estate development, cheap manufacturing labor, massive infrastructure outlays, and robust global trade integration—have reached their limits. The symptoms of this deceleration are no longer confined to macroeconomic balance sheets; they are visible in the daily lives of ordinary citizens. Youth unemployment has reached alarming heights, white-collar workers face relentless "involution" (neijuan) and layoffs in the tech and tutoring sectors, and consumer confidence remains depressed despite a litury of central bank interventions.
The psychological toll is profound. Just as the Rust Belt disillusionment in the United States shattered the American Dream for millions of industrial workers in the late 20th century, the current Chinese downturn is upending the social contract. That unspoken agreement—that the Communist Party would deliver unending material prosperity in exchange for political acquiescence—is facing its most severe stress test in decades.
Chronology: From Reform and Opening to the Great Slowdown
To understand the magnitude of the current psychological and economic shock in China, it is essential to trace the historical arc of the country’s modern development:
- The Early 1990s (The Launchpad): At the dawn of the decade, China’s per capita GDP was barely $300. Millions still lived at or near subsistence levels, and the country was just beginning to recover from the political and economic isolations of the late 1980s.
- The 2000s (The WTO Era and Urbanization): Following China’s accession to the World Trade Organization in 2001, the country became the "world’s factory." Skylines transformed overnight. Cities like Shenzhen, Shanghai, and Guangzhou filled with skyscrapers, multi-lane highways, and sprawling subway systems. Families transitioned rapidly from agrarian or basic industrial labor to the urban middle class.
- The 2008–2015 Infrastructure Boom: In response to the Global Financial Crisis, Beijing launched a massive 4-trillion-yuan stimulus package. This era saw the construction of the world’s largest high-speed rail network, unprecedented real estate expansion, and a surge in local government debt.
- The Late 2010s (Peak Optimism): China hosted global events, spearheaded the Belt and Road Initiative, and positioned itself as a technological superpower, rivaling the United States in artificial intelligence, 5G communications, and green energy technologies. Children attended elite universities in numbers their parents could scarcely have imagined.
- 2020–2022 (The Pandemic Crucible): "Zero-COVID" policies inflicted severe strain on consumer psychology, small businesses, and supply chains, abruptly halting the momentum of the urban consumer class.
- 2023–2026 (The Structural Realization): The collapse of major property developers like Evergrande and Country Garden triggered a protracted real estate slump. Local government financing vehicles (LGFVs) faced severe debt servicing crises, and the realization took hold that China had entered a "new normal" of structurally lower growth—mirroring the historical maturation and eventual stagnation of Western economies.
Supporting Data: The Numbers Behind the Pivot
A closer examination of economic indicators illustrates the stark contrast between the miracle decades and the current reality:
- GDP Per Capita: From a starting point of approximately $300 in 1990, China’s per capita GDP surged past $12,000 by the early 2020s, lifting over 800 million people out of extreme poverty. However, growth rates have steadily decelerated from the double-digit averages of the 2000s to official targets hovering around 5%, with many independent economists estimating true underlying growth to be significantly lower.
- The Property Sector: Historically accounting for nearly 30% of China’s total economic activity (including upstream and downstream industries), the real estate market has experienced a multi-year contraction. Property investment and new housing starts have plummeted by double digits annually since 2022, eroding household wealth, as real estate historically represented over 70% of Chinese household assets.
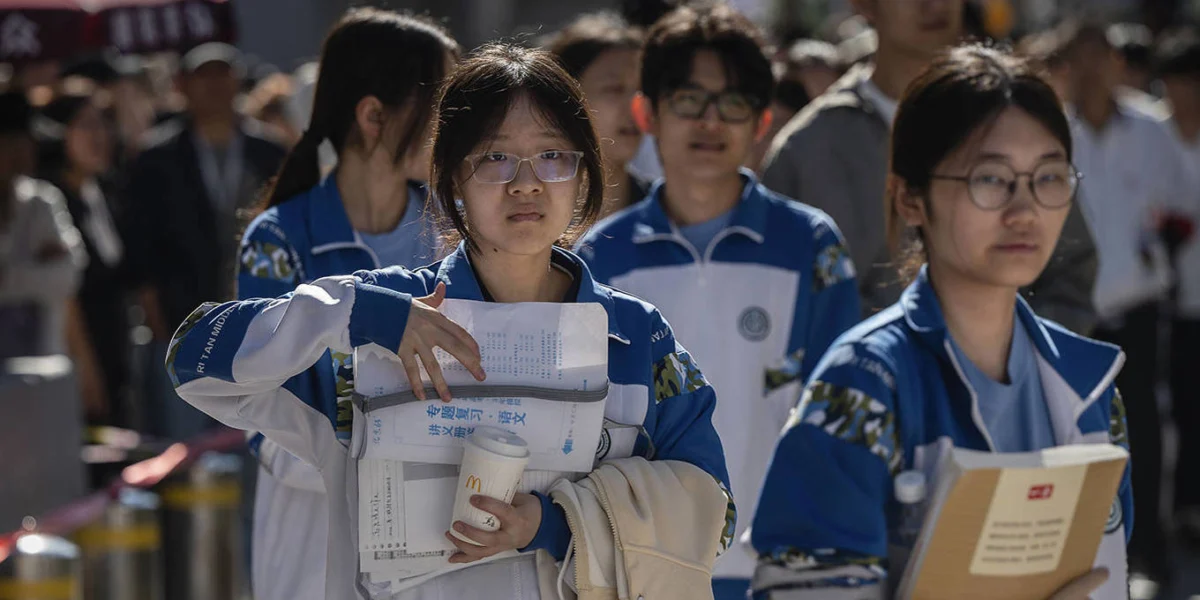
- Youth Unemployment: By mid-2023, the surveyed jobless rate for youth aged 16–24 surpassed 21.3%, prompting the National Bureau of Statistics to temporarily suspend data publication to recalibrate metrics. Even after methodological adjustments, structural job scarcity for college graduates—the generation expected to lead China’s high-value-add economy—remains a persistent crisis.
- Consumer Price Index (CPI): While Western economies battled historic inflation post-pandemic, China has frequently oscillated near deflationary territory. Weak domestic demand, overcapacity in manufacturing sectors like electric vehicles and solar panels, and cautious consumer spending have kept the CPI persistently low, signaling a chronic shortfall in aggregate demand.
Official Responses: Policy Maneuvers and Rhetorical Shifts
Beijing’s response to this structural slowdown has evolved from initial denial and localized interventions to a comprehensive, if cautious, series of monetary and fiscal stimulus measures.
Monetary and Fiscal Interventions
The People’s Bank of China (PBOC) has repeatedly cut reserve requirement ratios (RRRs) and lowered benchmark lending rates to inject liquidity into the banking system. Fiscal authorities have issued special sovereign bonds aimed at defusing local government debt risks and completing stalled housing projects—colloquially known as "tofu-dreg" or unfinished pre-sold apartments.
The Pivot to "New Quality Productive Forces"
Politically, the leadership has sought to reframe the economic narrative away from quantity toward quality. President Xi Jinping’s advocacy for "New Quality Productive Forces" (xin zhi shengchanli) emphasizes advanced manufacturing, biotechnology, aerospace, and green tech (the "New Three": EVs, lithium-ion batteries, and photovoltaic products). The state is attempting to engineer a supply-side upgrade, forcing out inefficient legacy industries while doubling down on high-tech self-reliance to insulate the economy from Western export controls.
Ideological Containment
Concurrently, official discourse has increasingly emphasized "common prosperity" and national security, aiming to manage public expectations. The state media frequently urges citizens to cultivate "bitter endurance" (chi ku)—a cultural throwback to earlier decades designed to foster resilience in the face of downward economic mobility.
Implications: A Parallel Disillusionment
The broader implications of China’s economic plateau extend far beyond its borders, fundamentally altering the geopolitical and social landscape of the 21st century.
Domestic Social Fabric
The psychological fallout in China closely mirrors the American experience of deindustrialization. When a society is conditioned to believe that each generation will decisively surpass the last, a sudden plateau feels like a betrayal. Millions of young urbanites who studied hard, entered top universities, and expected corporate or tech careers now find themselves competing for low-wage gig work or retreating from the job market entirely—a phenomenon embodied in viral internet subcultures like "lying flat" (tangping) and "letting it rot" (bailan).
This erosion of hope strikes at the heart of domestic stability. Just as the Rust Belt’s decline fueled political polarization and cultural grievance in the United States, China’s economic slowdown risks generating internal friction, forcing the state to rely more heavily on digital surveillance, ideological alignment, and appeals to nationalism to maintain cohesion.
Geopolitical Repercussions
Externally, a slower, more defensive China behaves differently on the global stage. Historically, the Chinese economic miracle acted as the primary locomotive for global growth, absorbing commodities from Latin America, machinery from Germany, and technology from Japan and South Korea. As domestic demand cools, Beijing has increasingly sought to export its industrial overcapacity to international markets, sparking severe trade friction with both the United States and the European Union. Tariffs on Chinese electric vehicles and green technology are the direct Western response to a Chinese economy trying to manufacture its way out of a domestic consumption slump.
Furthermore, economic insecurity often hardens foreign policy. A leadership grappling with internal economic anxieties may lean into external posturing, raising geopolitical tensions in the Taiwan Strait and the South China Sea as a mechanism to consolidate domestic support.
Conclusion
The parallel between China today and the United States of past decades lies in the painful realization that infinite growth is not an immutable law of economic physics. For a generation of Chinese citizens, the end of the miracle brings a bitter dose of realism. They are learning what Americans discovered decades ago: that managing decline, inequality, and dashed expectations is far more politically and socially fraught than managing the heady, frictionless days of an uninterrupted ascent.