Introduction and Executive Summary
Gold has long maintained its status as the ultimate safe-haven asset, but the economic landscape defining the yellow metal’s trajectory heading into 2026 is unprecedented. Driven by persistent macroeconomic uncertainties, shifting monetary policies from major central banks, geopolitical tensions, and robust institutional demand, the gold market is experiencing structural transformations.
Investors worldwide are recalibrating their portfolios in response to inflation anxieties, currency fluctuations, and fluctuating interest rate expectations. Within regional hubs such as the Kingdom of Saudi Arabia and Egypt, these global shifts manifest through distinct retail pricing trends, influencing consumer behavior, investment in gold bullions, and the broader economic outlook.
This comprehensive report examines the current state of gold prices, detailed regional data across Saudi Arabia and Egypt, the historical price performance through 2025, and expert economic projections for 2026.
Main Facts: The Macroeconomic Drivers of the 2025–2026 Gold Bull Market
The extraordinary performance of gold over the past two years is not an isolated market anomaly; rather, it is the cumulative result of deep-seated macroeconomic shifts. Understanding the current pricing environment requires analyzing the primary catalysts driving institutional and retail demand:

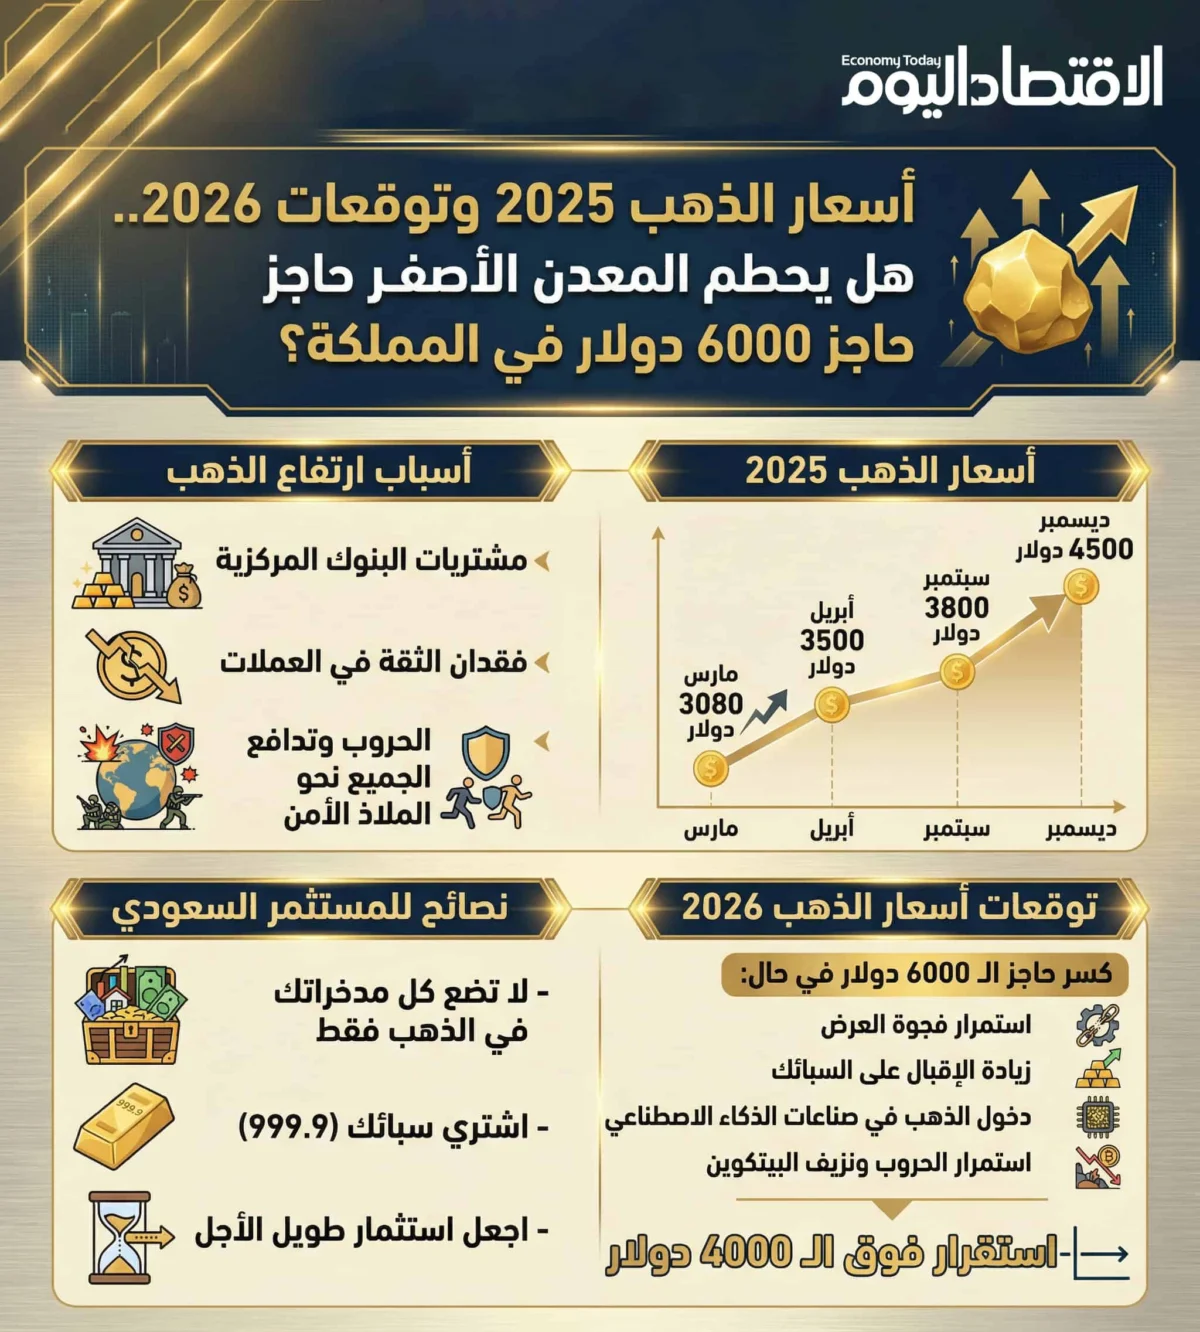
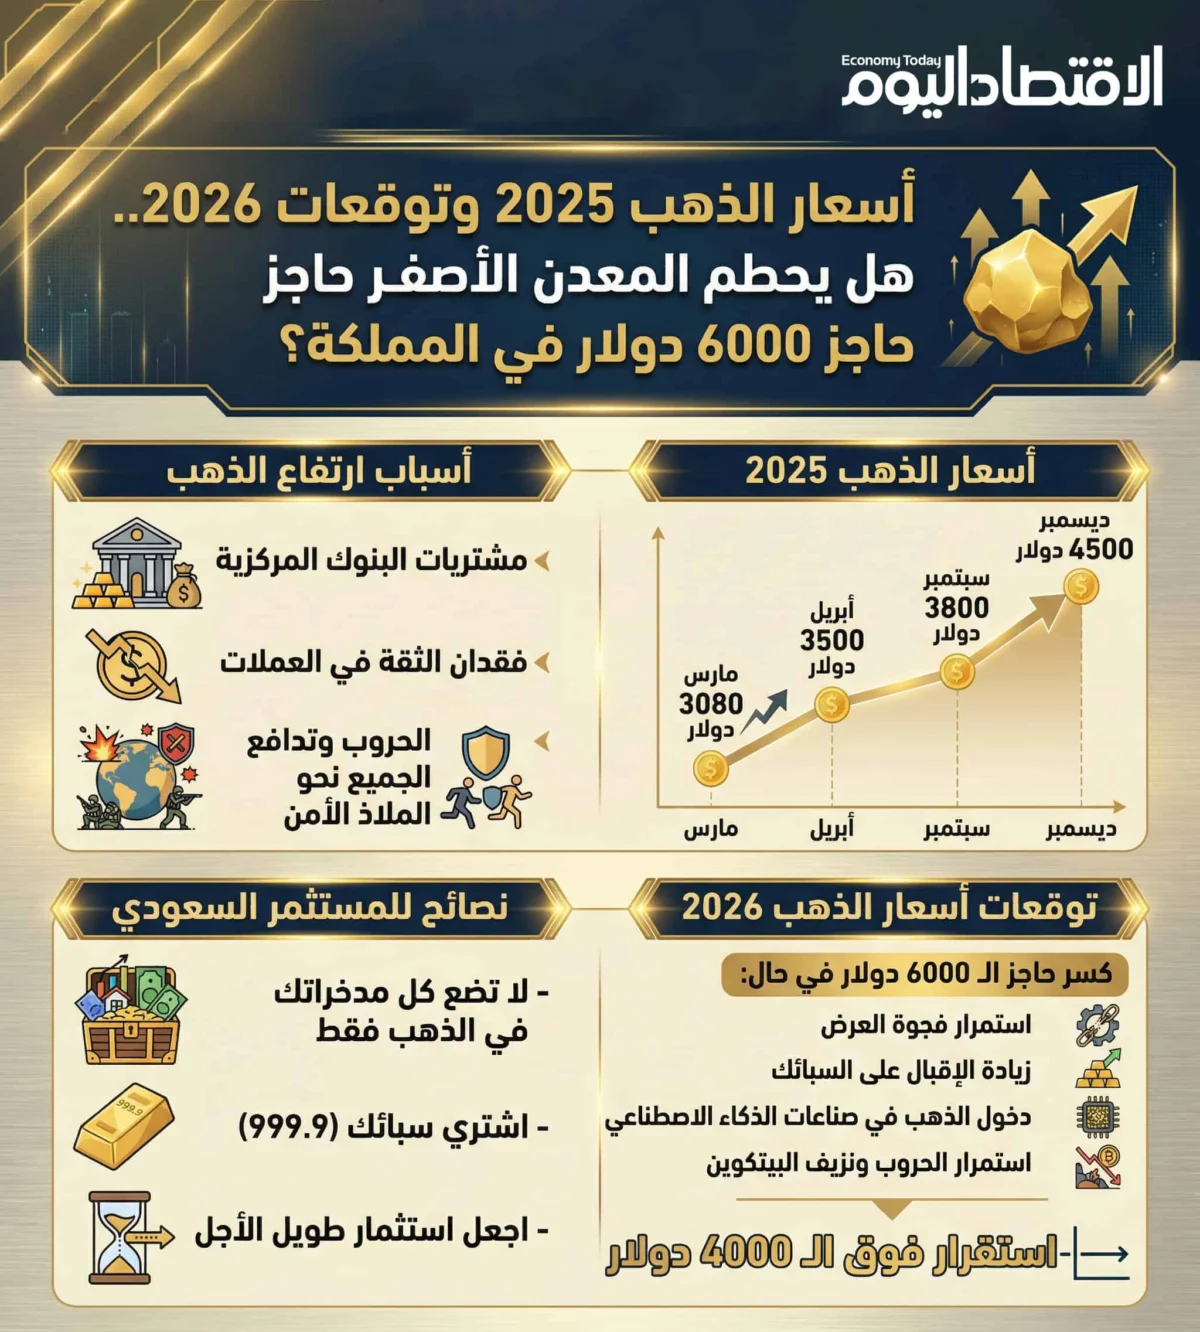
- Central Bank Accumulation: Central banks, particularly in emerging markets, have continued an aggressive multi-year trend of accumulating physical gold reserves. This strategic diversification away from fiat currencies—chiefly the U.S. dollar—has established a formidable price floor for the precious metal.
- Inflation Hedge and Currency Devaluation: Despite aggressive monetary tightening cycles initiated by global central banks in preceding years, structural inflationary pressures persist. Investors continue to utilize gold as a reliable hedge against the erosion of purchasing power.
- Geopolitical Volatility: Ongoing geopolitical flashpoints across Eastern Europe, the Middle East, and trade frictions among major global economies have heightened systemic risk perceptions. Capital consistently flees to gold during periods of elevated geopolitical uncertainty.
- Interest Rate Trajectory: Shifts in monetary policy expectations, particularly signaling by the U.S. Federal Reserve regarding interest rate adjustments, have directly influenced opportunity costs associated with holding non-yielding assets like gold. Anticipation of lower rates weakens sovereign bond yields and bolsters gold’s appeal.
Chronology of Market Movements: From 2025 Records to 2026 Projections
The journey of gold prices from the start of 2025 through early 2026 has been marked by record-breaking milestones and high volatility.
The 2025 Bull Run
Throughout 2025, gold prices demonstrated exceptional resilience, defying traditional economic models that suggested higher interest rates should suppress the metal. By the end of the third quarter of 2025, spot gold prices breached critical psychological milestones, challenging previous all-time highs. Analysts noted that continuous buying pressure from institutional investors and sovereign wealth funds propelled the market past the 4,500 currency-unit threshold in several regional trading desks.
As the fourth quarter of 2025 unfolded, retail demand surged in tandem with institutional accumulation. Jewelers, institutional portfolio managers, and individual retail investors engaged in active profit-taking mixed with strategic accumulation, ensuring that dips were aggressively bought.
Early 2026: Consolidation and New Horizons
Entering 2026, the gold market transitioned into a phase of heightened volatility coupled with upward structural consolidation. Market participants began closely monitoring whether the yellow metal could sustain its momentum and challenge even higher resistance levels—with speculative discussions centering on whether gold could test unprecedented highs in key regional markets.

The interplay between shifting currency valuations, local inflation metrics, and retail demand created a dynamic trading environment in key Middle Eastern markets, notably Saudi Arabia and Egypt.
Supporting Data: Regional Market Analysis (Saudi Arabia and Egypt)
Gold pricing mechanics vary significantly across international borders due to currency exchange rates, local import duties, manufacturing fees, and regional supply-demand dynamics.
Gold Market Dynamics in Saudi Arabia
In the Kingdom of Saudi Arabia, retail gold demand remains exceptionally robust. As a traditional store of value and an integral component of cultural and personal wealth preservation, Saudi consumers closely monitor daily spot rates for standard purities (primarily 24-karat, 21-karat, and 18-karat gold).
- Retail Preferences: While 24-karat gold remains the benchmark for pure bullion and investment bars (such as popular 50-gram and 1-kilogram bars), 21-karat and 18-karat gold dominate the local jewelry market.
- Market Transparency: The Saudi market operates in close correlation with international London Bullion Market Association (LBMA) spot prices, adjusted dynamically for local retail margins and fabrication fees. Local economic policies supporting diversification and robust foreign direct investment have further integrated Saudi retail markets with global financial trends.
Gold Market Dynamics in Egypt
The Egyptian gold market has experienced unique structural pressures driven by domestic currency fluctuations, inflationary adjustments, and domestic liquidity management.

- Price Volatility: Egyptian gold prices have historically reflected the interplay between global spot prices and the parallel or official exchange rates of the Egyptian Pound (EGP) against the U.S. dollar. When currency devaluation concerns rise, domestic demand for gold spikes dramatically as citizens seek to protect their savings.
- Benchmark Purity Metrics: Standard local pricing heavily features 24-karat gold, which traded at elevated levels (e.g., crossing 219,937 EGP per ounce equivalent metrics during peak tracking periods), alongside high demand for popular investment units such as 8-gram gold coins and certified local bullion bars.
- Consumer Adaptation: High domestic inflation has transformed gold from a luxury commodity into an essential financial instrument for middle- and lower-income households attempting to preserve capital against currency depreciation.
Official Responses and Industry Perspectives
Financial authorities, central bank officials, and leading bullion market analysts have maintained a watchful eye on the rapid appreciation of precious metals.
- Monetary Authorities: Central banks have reiterated that while gold plays a vital role in international reserves management, domestic monetary policy will continue to prioritize price stability and sustainable economic growth. Officials from regulatory bodies in the MENA region emphasize the importance of consumer protection, advising retail investors to purchase certified gold products from licensed bullion dealers to avoid counterfeit risks.
- Market Analysts: Senior commodity strategists point out that the structural shift in global reserve management—away from unbacked fiat instruments toward tangible hard assets—provides a strong baseline for gold prices. Industry experts interviewed by economic monitors suggest that structural corrections are healthy for the market, preventing speculative bubbles while offering sustainable entry points for long-term investors.
Implications for Investors and the Broader Economy
The sustained strength of gold carries profound implications for various economic stakeholders:
1. For Individual Investors
- Portfolio Diversification: Financial advisors recommend maintaining a balanced allocation of gold within a diversified investment portfolio (typically ranging from 5% to 15%, depending on individual risk tolerance). Gold acts as an effective shock absorber during equity market downturns.
- Form of Investment: Investors must weigh the pros and cons of physical gold (bars and coins) versus financial instruments (such as gold ETFs, mining stocks, or digital gold accounts). While physical gold offers tangible security, it incurs storage, insurance, and fabrication premiums.
2. For Central Banks and Macroeconomic Stability
- Reserves Enhancement: Continued gold purchases by sovereign entities signal a fundamental restructuring of global trade and reserve architectures. This trend reduces vulnerability to external financial sanctions and currency volatility.
- Retail Market Health: Robust retail demand supports local manufacturing sectors, jewelry artisans, and specialized bullion dealers, contributing positively to local commerce despite broader inflationary headwinds.
Conclusion
As the global economy navigates the complexities of 2026, gold remains a central pillar of financial security and wealth preservation. Whether analyzed through the lens of international macroeconomic drivers, regional pricing structures in Saudi Arabia and Egypt, or long-term institutional strategies, the yellow metal continues to command unmatched authority in financial markets.
Investors are advised to maintain a disciplined, long-term perspective, paying close attention to macroeconomic indicators, central bank policies, and geopolitical developments as the gold market charts its course through the remainder of the decade.