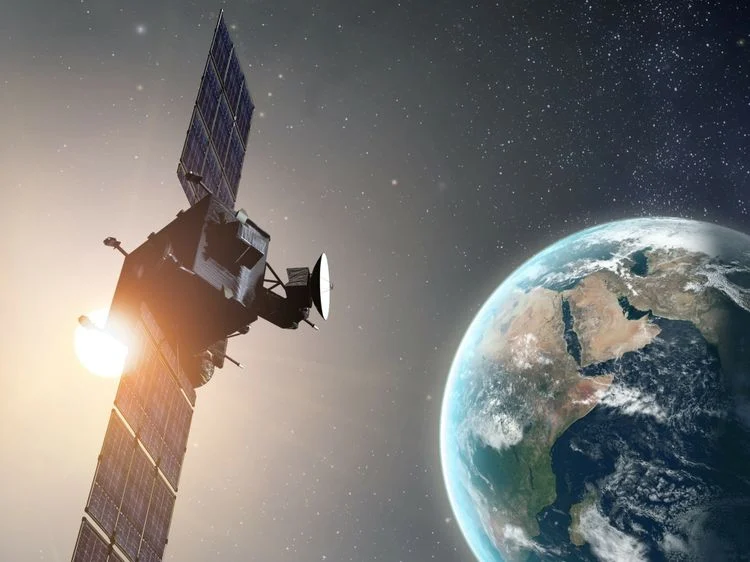
Global military satellite communications are undergoing a paradigm shift, transitioning from legacy geostationary networks to resilient, multi-orbit architectures designed to withstand advanced electronic and kinetic warfare.
Main Facts
The global military satellite communications (satcom) landscape is on the brink of an unprecedented financial and technological expansion. According to the newly released Satellite Communications for Defense and Security (2nd Edition) report by space consulting and market intelligence firm Novaspace, commercial satellite service revenues dedicated to defense and security will surge to exceed $22.6 billion by 2035.
Simultaneously, global defense satcom demand is projected to skyrocket, surpassing 7.5 Terabits per second (Tbps) over the next decade. This rapid acceleration is primarily being catalyzed by the aggressive global adoption of next-generation non-geostationary orbit (NGSO) constellations.
While traditional Geostationary Earth Orbit (GEO) satellites will continue to hold a foundational role in military networking—with GEO capacity demand forecast to triple—their financial footprint is expected to evolve. GEO service revenues will decline from $2.3 billion in 2025 to $1.3 billion by 2035 as multi-orbit strategies take precedence. In stark contrast, NGSO service revenues are projected to experience an astronomical Compound Annual Growth Rate (CAGR) of 34%, culminating in $21.3 billion by 2035.
Geographically, the United States will remain the undisputed heavyweight in the military satcom ecosystem, accounting for more than 50% of global demand and 48% of total revenues by 2035. China will follow as the second-largest market, capturing approximately 30% of global demand and revenues.
Chronology of Market Evolution: From Single-Orbit Reliance to Multi-Orbit Resilience
To understand the magnitude of the 2035 projections, it is essential to trace the historical trajectory of military satellite communications and how geopolitical pressures have accelerated technological adoption over recent years.
The Legacy Era (Pre-2020)
For decades, military satcom relied almost exclusively on dedicated, high-cost military-grade Geostationary Earth Orbit (GEO) satellites. While these systems provided stable, wide-area coverage, they suffered from significant vulnerabilities: high latency, massive capital expenditure requirements, and extreme vulnerability to kinetic attacks, signal jamming, and cyber interference. A single jammer could neutralize a critical theater of operations.
The Commercial Awakening (2020–2024)
As asymmetric warfare and electronic countermeasures evolved, military leadership recognized that legacy systems alone could not guarantee mission assurance. The early 2020s marked a turning point where defense agencies began actively integrating commercial satellite operators into their communication grids. Low Earth Orbit (LEO) constellations—championed by commercial broadband pioneers—began proving their worth in real-world geopolitical conflicts, demonstrating that commercial agility could outpace traditional defense procurement cycles.
The Multi-Orbit Convergence (2025–Present)
Marked by the release of Novaspace’s inaugural Satellite Communications for Defense and Security report in 2025 and reinforced by this newly published 2nd Edition, the industry has formally entered the "Multi-Orbit Era." Defense procurement agencies worldwide are no longer asking if they should use commercial NGSO assets, but how deeply they can embed them into resilient, layered architectures.
Supporting Data & Market Metrics
The Novaspace report provides a granular breakdown of the financial and operational shifts defining the next decade of defense satcom.
- Total Revenue Projection (2035): Commercial satellite services for defense will exceed $22.6 billion.
- Aggregate Global Demand: Expected to scale past 7.5 Tbps by 2035.
- NGSO Revenue Growth: Projected to reach $21.3 billion by 2035, underpinned by a remarkable 34% CAGR.
- GEO Capacity vs. Revenue Dynamic: While raw GEO capacity demand is forecast to triple to meet continuous baseline military data needs, overall GEO revenues will contract from $2.3 billion (2025) to $1.3 billion (2035) due to pricing pressures and the cost-efficiency of NGSO alternatives.
- Geographic Distribution of Power:
- United States: >50% of global demand; 48% of global revenues by 2035.
- China: ~30% of global demand and revenues.
- Rest of the World: The remaining ~20% distributed among allied blocs (NATO, Indo-Pacific partners) and emerging space-faring nations.
Official Responses and Expert Insights
Industry leaders and market analysts have emphasized that these numbers reflect a permanent structural change in how modern armed forces conceptualize operational security and battlefield communication.
Santiago Perez, Senior Manager at Novaspace, highlighted the strategic imperative driving these multi-billion-dollar investments:
"The growing adoption of distributed satcom architectures is rapidly enhancing military satcom resilience against disruption, jamming, and kinetic attacks. As defense users increasingly adopt multi-orbit connectivity strategies, NGSO constellations will play a pivotal role in delivering the capacity, low latency, and resilience required for future military operations."
Perez further underscored that this is not merely a quantitative upgrade in bandwidth, but a qualitative transformation in military doctrine:
"What we’re witnessing is not simply a shift in satellite capacity demand. This is a fundamental evolution in military communications. Multi-orbit connectivity is becoming the foundation of modern defense networks and will shape procurement, operations, and strategic planning for years to come."
Strategic Implications for Global Defense and Industry
The transition toward a commercial-military hybrid satcom model carries profound implications for defense contractors, sovereign space agencies, and commercial satellite operators alike.
1. Hardening Against Electronic and Kinetic Warfare
Modern warfare—exemplified by conflicts in Eastern Europe and the Middle East—has demonstrated that space assets are primary targets for electronic warfare, GPS spoofing, and high-powered microwave or kinetic anti-satellite (ASAT) weapons. By shifting toward distributed, multi-orbit architectures (combining GEO, Medium Earth Orbit, and Low Earth Orbit), defense networks eliminate single points of failure. If one LEO satellite or orbital plane is jammed or disabled, data packets are automatically rerouted across alternative nodes within milliseconds.
2. Shifts in Defense Procurement and C4ISR
Traditional defense procurement has long been criticized for lengthy acquisition cycles that render hardware obsolete by the time it is deployed. By leaning heavily into commercial NGSO ecosystems, military agencies can tap into rapid commercial innovation cycles. This allows defense forces to upgrade their Command, Control, Communications, Computers, Intelligence, Surveillance, and Reconnaissance (C4ISR) capabilities at the speed of commercial technology adoption rather than traditional defense budgeting timelines.
3. Geopolitical Competition and the U.S.–China Duopoly
With the United States and China commanding a combined 80% of global defense satcom demand and revenues, the market reflects broader geopolitical competition for space dominance. The U.S. Department of Defense’s implementation of initiatives like the Proliferated Warfighter Space Architecture (PWSA) mirrors China’s development of massive state-backed mega-constellations. This duopoly will likely spur a secondary space race among allied nations (such as European Union members, Japan, India, and Australia) to secure independent, sovereign secure communication channels to avoid total reliance on American or Chinese commercial infrastructure.
4. Opportunities for Commercial Operators
For commercial satellite operators, the defense sector is transitioning from an opportunistic secondary customer base to an anchor tenant providing predictable, long-term multi-billion-dollar revenue streams. Operators that can meet stringent military-grade cybersecurity protocols, sovereign data-routing requirements, and end-to-end encryption standards stand to capture the lion’s share of the $22.6 billion market by 2035.
For further details, the full Satellite Communications for Defense and Security (2nd Edition) report is available directly through Novaspace. Novaspace itself operates as a premier market intelligence entity formed via the strategic merger of Euroconsult and SpaceTec Partners.