
For the better part of eight months, the price of diesel has climbed to staggering heights that gasoline has not come close to matching. For a motor carrier whose single largest variable cost is the fuel sitting in the tank, this historic market split is far more than an economic curiosity—it is a direct, violent blow to the bottom line.
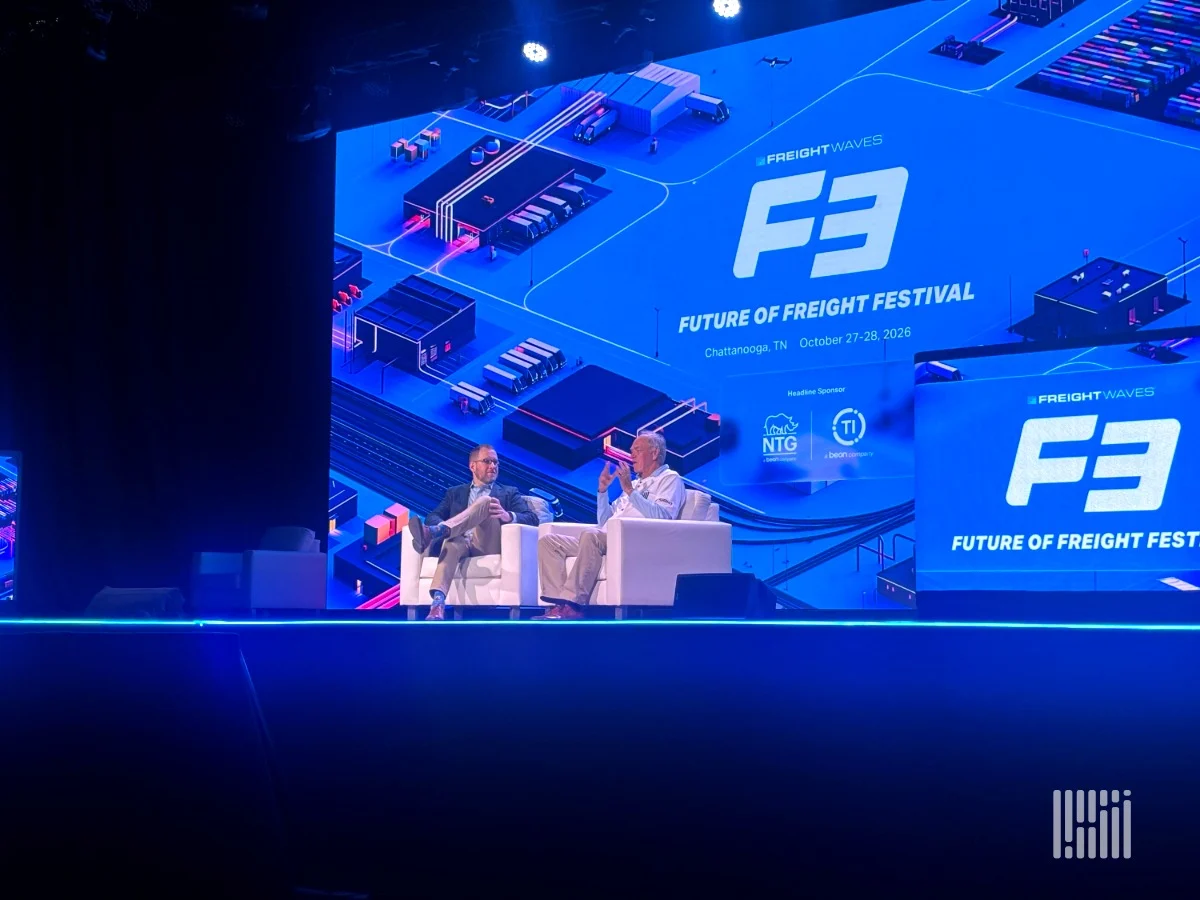
To understand why this is happening, the freight sector must look past traditional headline metrics. In a recent conversation at the Future of Freight Festival (F3) with Patrick De Haan, head of petroleum analysis at GasBuddy—who has tracked retail pump prices since 2009—industry leaders gained a stark new perspective. The forces driving diesel to unprecedented records have far less to do with the spot price of crude oil than almost anyone standing at the fuel counter assumes.
Main Facts: The Anatomy of a Fuel Market Split
The numbers tell the story of a dramatic divergence. According to De Haan, whose firm tracks gasoline and diesel at roughly 150,000 stations across the United States and Canada, diesel blew past its previous 2022 record of $5.81 per gallon. It touched nearly $6.50 a gallon weeks prior before easing slightly to hover around $6.35.
Gasoline, by contrast, has stubbornly held ground roughly 70 cents below its own 2022 historic highs, averaging about $4.26 per gallon.
┌────────────────────────┬──────────────────┬──────────────────┐
│ Fuel Type              │ 2022 Peak Record │ Current Pricing  │
├────────────────────────┼──────────────────┼──────────────────┤
│ Diesel                 │ $5.81 / gal      │ ~$6.35 / gal     │
│ Gasoline               │ ~$4.96 / gal     │ ~$4.26 / gal     │
└────────────────────────┴──────────────────┴──────────────────┘
During the last comparable inflationary shock in post-pandemic 2022, gasoline and diesel set records almost simultaneously, moving in tandem. This time, however, the two fuels have uncoupled entirely. This decoupling has forced consumers and commercial carriers alike to realize a fundamental truth they rarely have to consider: gasoline, diesel, jet fuel, and crude oil are distinct products governed by entirely different economic rules. A barrel of crude oil is virtually worthless until a refinery transforms it into something usable.
This realization is the central hinge of De Haan’s market analysis. While the public fixates on the global price of crude, unrefined oil is useless. The true narrative of the past year is not a shortage of oil in the ground, but rather a severe constraint on global refining capacity.
Chronology: How the Crisis Unfolded
The current market volatility did not appear overnight. Tracing the timeline reveals a sustained period of turbulence that defies normal seasonal patterns.
- March 2026: Market expectations of a massive global crude glut abruptly shatter. The steady, predictable pricing environment predicted by analysts vanishes overnight. Wholesale fuel markets experience wild, intraday price swings where filling a transport truck at 5:55 PM versus 6:05 PM yields a 50- to 80-cent-per-gallon difference.
- March – April 2026: The "rack"—the wholesale level where fuel is purchased before retail distribution—begins resetting multiple times a day instead of its historical once-daily schedule.
- June – July 2026: Prices experience a brief, deceptive cooling period, giving carriers a temporary reprieve.
- August – September 2026: The market roars back with a vengeance. Driven by geopolitical shocks and structural supply pinches, diesel surges past previous boundaries.
- Late October 2026: Retail prices stubbornly lock in at extreme highs ($4.26 for gasoline; $6.35 for diesel), leaving long-term relief entirely out of reach as the industry heads toward the winter shipping season.
Supporting Data: Refining Complexities and Regional Disparities
Why Refining Dictates the Diesel Squeeze
Not all crude oil is created equal. De Haan compared the crude market to the oil aisle at an auto parts store, where there is no single weight or grade. Refineries are built to process specific blends—ranging from light, sweet crudes to heavier grades produced by Canada, Venezuela, Iran, and Russia.
Crucially, heavier crude inputs yield a higher percentage of heavy products like diesel. The countries sitting at the epicenter of this year’s geopolitical disruptions are precisely those heavy-crude players:
- Iran: Operates at roughly 55% heavy crude production.
- Venezuela: Continues to navigate long-standing regulatory and operational hurdles over hard-to-refine heavy barrels.
Furthermore, a refinery cannot simply swap one type of crude for another on a whim. When heavy barrels or the complex facilities required to process them face operational pressure, diesel feels the shock first.
This structural vulnerability is compounded by long-term shifts in global capacity. Diesel has historically traded above gasoline for roughly two decades—a structural gap that widened after ultra-low-sulfur diesel (ULSD) specifications took effect around 2006. Compounding this, the United States has lost its crown as the world’s largest refiner, having been overtaken by China. China has deliberately throttled some of its refining output to protect domestic crude access and strategic reserves, siphoning critical capacity out of an already tight global market.
The Russia-Ukraine Shock
Layered on top of these structural limitations is a fast-moving geopolitical crisis. De Haan pointed to an exponential jump in diesel starting in July, directly tied to Russia scaling back diesel exports. Russia typically accounts for roughly 10% of the world’s diesel supply.
This export contraction is the direct result of an escalating Ukrainian drone campaign against Russian refineries. While these strikes began last October, they have grown significantly more precise and effective over the past year. The sustained degradation of Russia’s refining infrastructure has forced domestic fuel rationing within Russia, sharply reducing the volume available for international export. When stacked on top of existing Middle Eastern tensions—such as disruptions near the Strait of Hormuz affecting crude flows—the market is bearing a dual-layer pressure: a crude-price shock compounded by a severe refining-capacity loss.
How Regional Infrastructure Builds the Pump Price
To understand why two motor carriers operating in different states pay drastically different prices on the same day, one must examine the physical pipeline architecture of North America.
The foundation for wholesale diesel across the continent is the NYMEX ultra-low-sulfur diesel contract—essentially a delivered New York Harbor price for barge-transported fuel, stripped of taxes. From that baseline, regional refining balances dictate local pricing. Spreads between markets can fluctuate by 40 to 60 cents per gallon depending on the state.
- The Gulf Coast & Colonial Pipeline: The Colonial Pipeline acts as a massive energy aorta running from the Houston area up through the mid-Atlantic to New York. Because the Gulf Coast houses the densest collection of refining capacity in the country, it is typically one of the cheapest places to buy fuel. However, when Europe scrambles to replace lost Russian diesel, Gulf Coast fuel is increasingly diverted to export markets, causing domestic prices along the pipeline to spike.
- The West Coast: Consistently maintains the highest prices in the nation due to stringent state environmental policies that have systematically narrowed refining capacity, combined with heavy state fuel taxes.
- The Great Lakes: Recent price spikes in this region were driven by localized refining hiccups, as Great Lakes plants lean heavily on Western Canadian crude inputs.
Official Responses and Industry Analysis
Assessing responsibility for the crisis, De Haan took a measured stance, arguing that oil companies are fundamentally "price takers" rather than "price makers." He noted that earlier in the year—before the current market breaks—crude sat at a modest $50 to $60 a barrel, a range where upstream producers were hardly thriving. Convenience store retailers, meanwhile, have seen retail margins run unusually high, insulating themselves by driving profits through non-fuel in-store sales while navigating wholesale volatility.
De Haan characterized this stretch as the single most volatile period he has witnessed in 26 years of tracking the industry. Unlike historical spikes driven by transient events like hurricanes or sudden geopolitical flare-ups—which typically resolve in a week or two—the current disruption has run continuously since early spring.
Industry forecasters heading into the year widely predicted a global crude glut. That consensus expectation shattered abruptly on March 1, leaving the market without a clear path back to calm, well-supplied equilibrium.
Implications for Motor Carriers and Supply Chains
For commercial trucking operations, the mechanics of this decoupled market create a dangerous lag in cost recovery.
The Broken Fuel Surcharge Mechanism
Most motor carrier fuel surcharge (FSC) programs are pegged directly to the U.S. Department of Energy’s (DOE) weekly national average on-highway diesel price—a single benchmark published once a week.
In a traditional market, this index works adequately. But in a market where wholesale rack prices can swing by nearly a dollar within minutes, and regional spreads vary by half a dollar or more, a weekly national average cannot keep pace.
Furthermore, retail stations turn over their underground storage tanks much faster than commonly assumed—typically every two to four days, and even more frequently at high-volume truck stops. The outdated notion that a station is selling fuel priced ten days ago is entirely false.
Consequently, a carrier running expensive lanes—such as the West Coast, the Great Lakes during a refinery outage, or the Gulf Coast during an export surge—pays well above the national index. Because the DOE index lags both the initial price spike and the eventual recovery, the financial gap between real-world pump costs and surcharge reimbursements comes directly out of carrier operating margins.
Strategic Takeaways for Fleet Operators
- Stop Tracking Crude Alone: Planning fleet fuel budgets around the headline price of West Texas Intermediate (WTI) or Brent crude is tracking the wrong metric. Diesel is governed by independent refining margins and middle-distillate inventory levels.
- Audit Surcharge Formulas: Shippers and carriers must recognize that standard weekly surcharges recover significantly less of the true cost in a refining-driven, decoupled market than they did historically.
- Monitor Regional Vulnerabilities: Fleet route planning must account for regional refining bottlenecks, pipeline flows, and local policy pressures, treating fuel variance as an active risk variable to be continually managed rather than an assumed operational baseline.
Ultimately, diesel has permanently severed its traditional correlation with gasoline and crude oil. For anyone whose business model lives and dies at the fuel island, survival in this new paradigm requires tracking diesel strictly on its own terms, understanding the complex regional forces setting the pump price, and treating margin protection as an urgent, ongoing operational discipline.